Can You Recover Lost Earning Capacity After an Accident?
Can you recover lost earning capacity after an accident? Yes, if you can prove it. Call 8555452917 for a free case review and protect your future income.
By Orion Hale
A serious injury does not just hurt your body. It can quietly dismantle your financial future. You may return to work at a lower wage, lose a promotion, or never work again. When that happens, the law gives you a path to seek compensation for what you would have earned. The question, can you recover lost earning capacity after an accident, has a clear answer in most personal injury cases: yes, if you can prove it. This article explains what lost earning capacity means, how it differs from lost wages, how courts and insurers evaluate it, and the practical steps that strengthen your claim.
What Lost Earning Capacity Actually Means
Lost earning capacity is not the same as lost wages. Lost wages cover the paychecks you missed immediately after the accident, usually while you were recovering or attending medical appointments. Lost earning capacity is broader. It represents the difference between what you could have earned over your working life if the injury had never happened and what you can realistically earn now.
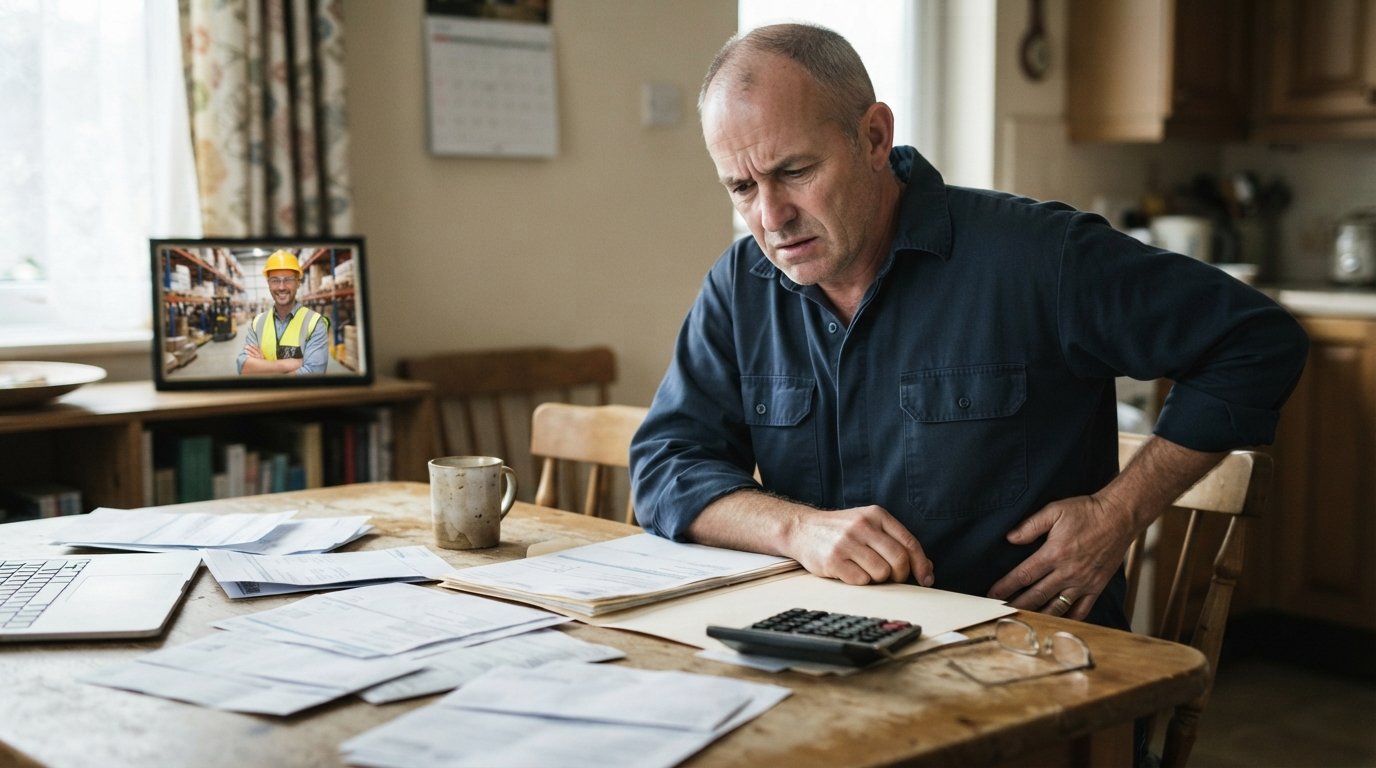
Imagine a warehouse supervisor who earns $60,000 per year. After a spinal injury, he can only perform sedentary work paying $35,000. His lost earning capacity claim could seek the $25,000 annual difference, projected across the remaining years he intended to work. For a younger worker or a high earner, that number can reach hundreds of thousands or even millions of dollars.
Courts treat earning capacity as an asset. Damaging it is like damaging property. You are entitled to compensation for the diminished value of that asset, provided you can prove the loss with reasonable certainty. Speculation is not enough, but you also do not need mathematical perfection. Evidence, expert testimony, and consistent documentation carry the claim.
How Lost Earning Capacity Differs From Lost Wages
The distinction matters because insurance adjusters often try to blend the two and pay only the smaller number. Lost wages are past losses, easy to calculate from pay stubs and tax returns. Lost earning capacity is future loss, which requires projection. A claim for lost wages might cover six weeks of missed work. A claim for lost earning capacity might cover twenty years of reduced income.
In many states, you can pursue both. The past wage loss compensates what you already missed. The lost earning capacity compensates what you will miss going forward. If your injury permanently limits your hours, the type of work you can perform, or your ability to advance, the future component is often the larger part of the case.
There is also a subtle difference between actual loss and theoretical loss. Suppose you were unemployed at the time of the accident but actively interviewing. You may still have a lost earning capacity claim because your capacity to earn existed, even if you were not currently collecting a paycheck. Likewise, a stay-at-home parent who planned to re-enter the workforce can seek damages if the injury destroys that plan.
How Courts and Insurers Calculate Lost Earning Capacity
There is no single formula. Jurisdictions use different methods, and the calculation depends heavily on the facts. However, most evaluations combine several factors that together paint a picture of your economic future before and after the injury.
Key factors typically include your age, education, work history, skills, medical prognosis, and the physical demands of your prior occupation. A 55-year-old with a stable career and a permanent lifting restriction may have a more predictable loss than a 25-year-old whose career trajectory is still developing. Vocational experts and economists are often hired to translate those facts into a dollar figure.
Here are the main approaches you will see in practice:
- The before-and-after method: Compare your pre-injury earnings capacity with your post-injury capacity. The difference, projected over your remaining work life, becomes the claim.
- The loss-of-competitive-edge method: Even if you still work, the injury may prevent you from competing for raises, promotions, or physically demanding roles. This method values the opportunities you lost.
- The vocational expert method: A specialist reviews your medical records, job history, and transferable skills to identify what work you can realistically perform now and what it pays.
- The economic projection method: An economist applies growth rates, inflation, and present-value discounts to convert future losses into today's dollars.
Each method has strengths and weaknesses. Insurers often attack projections as too speculative, especially for younger victims or those with irregular work histories. Plaintiffs counter with detailed documentation, expert testimony, and consistent medical evidence. The stronger your records, the harder it is for the other side to dismiss your future loss as guesswork.
Evidence That Strengthens a Lost Earning Capacity Claim
Winning a lost earning capacity claim is largely about proof. You must show that the injury caused a real, measurable reduction in your ability to earn. That requires more than your own testimony, though your testimony matters. It requires a documented trail of medical, vocational, and financial evidence.
Start with medical records. Treating physicians should describe your permanent restrictions, pain levels, and prognosis. If a doctor says you cannot lift more than 20 pounds or sit for more than an hour, that statement directly limits the jobs available to you. A functional capacity evaluation can also provide objective measurements of what you can and cannot do.
Financial records are equally important. Collect pay stubs, W-2s, tax returns, performance reviews, and promotion letters. If you were self-employed, gather profit-and-loss statements and client contracts. These documents establish your earning baseline. Without them, the defense will argue your pre-injury income was lower than you claim.
Vocational evidence ties the medical and financial pieces together. A vocational expert can testify that your restrictions prevent you from returning to your prior field and that the jobs you can still perform pay significantly less. An economist then converts that gap into a present-value figure. Together, these experts give the jury or adjuster a concrete number to consider.
Finally, keep a personal journal. Record how the injury affects your daily energy, your ability to concentrate, and the tasks you can no longer perform. While not a substitute for expert proof, a journal adds human context and can support your credibility.
Common Challenges and How to Address Them
Insurers rarely accept a lost earning capacity claim at face value. They look for reasons to reduce or deny it. Knowing the common challenges ahead of time helps you prepare a stronger case.
One frequent argument is that the victim failed to mitigate damages. If you refused reasonable medical treatment or turned down suitable light-duty work, the defense may argue you made your losses worse. Follow your doctor's advice, document your job search, and accept appropriate modified work when it is genuinely available.
Another challenge involves pre-existing conditions. If you had a bad back before the accident, the defense will claim your current limitations are unrelated. This is where careful medical testimony matters. Your doctor must explain how the accident aggravated or accelerated the prior condition and how that aggravation affects your earning capacity.
Self-employed victims face unique hurdles. Their income can fluctuate, and the defense may argue the business was already declining. Strong bookkeeping, tax records, and testimony from long-term clients can counter that narrative. In some cases, an accountant or business valuation expert can clarify the true impact.
Finally, younger victims often face skepticism because their careers are not yet established. Courts still recognize these claims, but they require thoughtful vocational evidence. A vocational expert can identify a realistic career path and compare it with the post-injury path. The goal is not to assume you would have become a CEO, but to show a reasonable trajectory based on your skills and interests.
If you admitted fault at the scene or made statements that minimized the other driver's responsibility, that can complicate your claim. Our guide on why admitting fault can cost you explains how early statements can be used against you and what to do instead.
Steps to Take After an Accident to Protect Your Future Earnings
The actions you take in the days and weeks after an accident can make or break a lost earning capacity claim. Evidence disappears, memories fade, and insurers move quickly to limit exposure. Being proactive protects your rights and preserves the proof you will need later.
First, seek medical attention immediately, even if you feel fine. Some injuries, like whiplash or traumatic brain injuries, do not show symptoms right away. A prompt diagnosis creates a medical record linking your condition to the accident. Follow all treatment recommendations and attend every appointment. Gaps in treatment are often used to argue you were not seriously hurt.
Second, report the accident to the police and obtain a copy of the report. Do not discuss fault with the other driver or the insurance company. Stick to the facts and avoid speculation. If an adjuster asks for a recorded statement, politely decline until you have spoken with an attorney.
Third, document everything. Take photos of the scene, your injuries, and your vehicle damage. Save receipts for medical bills, prescriptions, and travel to appointments. Keep a folder with pay stubs, tax returns, and performance reviews. These records form the foundation of your lost earning capacity calculation.
Fourth, consult a personal injury attorney who handles lost earning capacity claims. An experienced lawyer can retain the right experts, calculate your future losses, and negotiate with insurers who may try to undervalue your claim. Many attorneys offer free consultations and work on a contingency fee, meaning you pay nothing unless they recover compensation for you.
If you are looking for legal resources to organize your case, platforms like FormsByLawyers can connect you with attorneys and forms for personal injury matters. However, for a claim as complex as lost earning capacity, personalized legal representation is usually the better path.
How a Lawyer Can Help You Recover Lost Earning Capacity
An attorney levels the playing field against insurance companies. Insurers employ teams of adjusters, lawyers, and experts whose job is to minimize payouts. A skilled personal injury lawyer knows how to counter those tactics and present your lost earning capacity claim in its strongest light.
Your lawyer will investigate the accident, gather medical records, and consult with vocational and economic experts. They will calculate a defensible number for your future loss, taking into account your age, career trajectory, and permanent restrictions. They will also handle all communication with the insurance company, protecting you from making statements that could hurt your case.
If the insurer refuses to offer a fair settlement, your lawyer can file a lawsuit and take the case to trial. The threat of trial often pushes insurers to negotiate seriously. Even if your case settles, having a lawyer from the start typically results in a higher net recovery, even after attorney fees.
CarInjuryAccident.com connects injured people with a network of experienced attorneys across the country. The platform uses a patented attorney selection process to identify top-rated legal professionals. You can request a free, confidential case evaluation with no obligation to hire. If you are unsure where to start, this is a low-risk way to get professional eyes on your claim.
Frequently Asked Questions About Lost Earning Capacity
Can I recover lost earning capacity if I was unemployed at the time of the accident?
Yes, in many cases. Lost earning capacity is about your ability to earn, not just your current paycheck. If you were actively seeking work, in school, or planning to return to the workforce, you may still have a claim. You will need evidence of your work history, skills, and intentions.
How long do I have to file a lost earning capacity claim?
Every state has a statute of limitations for personal injury claims, typically ranging from one to three years. Missing the deadline can bar your claim entirely. Consult an attorney as soon as possible to protect your rights.
Do I need an expert witness to prove lost earning capacity?
Not always, but experts make the claim much stronger. Vocational experts and economists provide objective analysis that juries and adjusters find persuasive. In complex or high-value cases, expert testimony is often essential.
What if the insurance company offers a quick settlement?
Be cautious. Early offers usually do not account for future losses like lost earning capacity. Once you accept a settlement, you cannot go back for more. Have an attorney review any offer before signing.
Recovering lost earning capacity after an accident is possible, but it requires proof, persistence, and often professional help. The sooner you act, the better your chances of preserving evidence and building a strong claim.