Chapter 7 Trustee Meeting of Creditors: Questions to Expect
Facing a Chapter 7 trustee meeting? Know the questions to expect and how to prepare. Call 8555452917 for a free case evaluation today.
By Elvara Quinn
The Chapter 7 trustee meeting of creditors, often called the 341 meeting, is the moment many bankruptcy filers dread most. You have filed your petition, gathered years of financial records, and paid the filing fee. Now you must sit across from a court-appointed trustee who will question you under oath about your assets, debts, and recent financial history. Knowing what questions to expect can turn a nerve-wracking appearance into a manageable, even routine, conversation that lasts only a few minutes.
Most consumer Chapter 7 cases involve a short hearing. The trustee asks a standard set of questions, reviews your identification and documents, and then moves to your case. The entire proceeding often takes less than ten minutes. However, the answers you give matter. Inconsistencies between your testimony and your bankruptcy schedules can delay your discharge or, in rare cases, lead to a denial of your case. Preparation is not about memorizing a script; it is about understanding why the trustee asks each question and how to answer truthfully and clearly.
This guide explains the purpose of the meeting, the specific questions you are likely to hear, how to prepare documents, and what happens if the trustee probes deeper into your finances. It also covers common mistakes that create unnecessary problems and explains when you should consult a bankruptcy attorney before your hearing. If you are also concerned about the cost of legal help, our guide on Chapter 7 bankruptcy lawyer fees explained breaks down typical fee structures and what to expect from your representative.
What Is the Chapter 7 Trustee Meeting of Creditors?
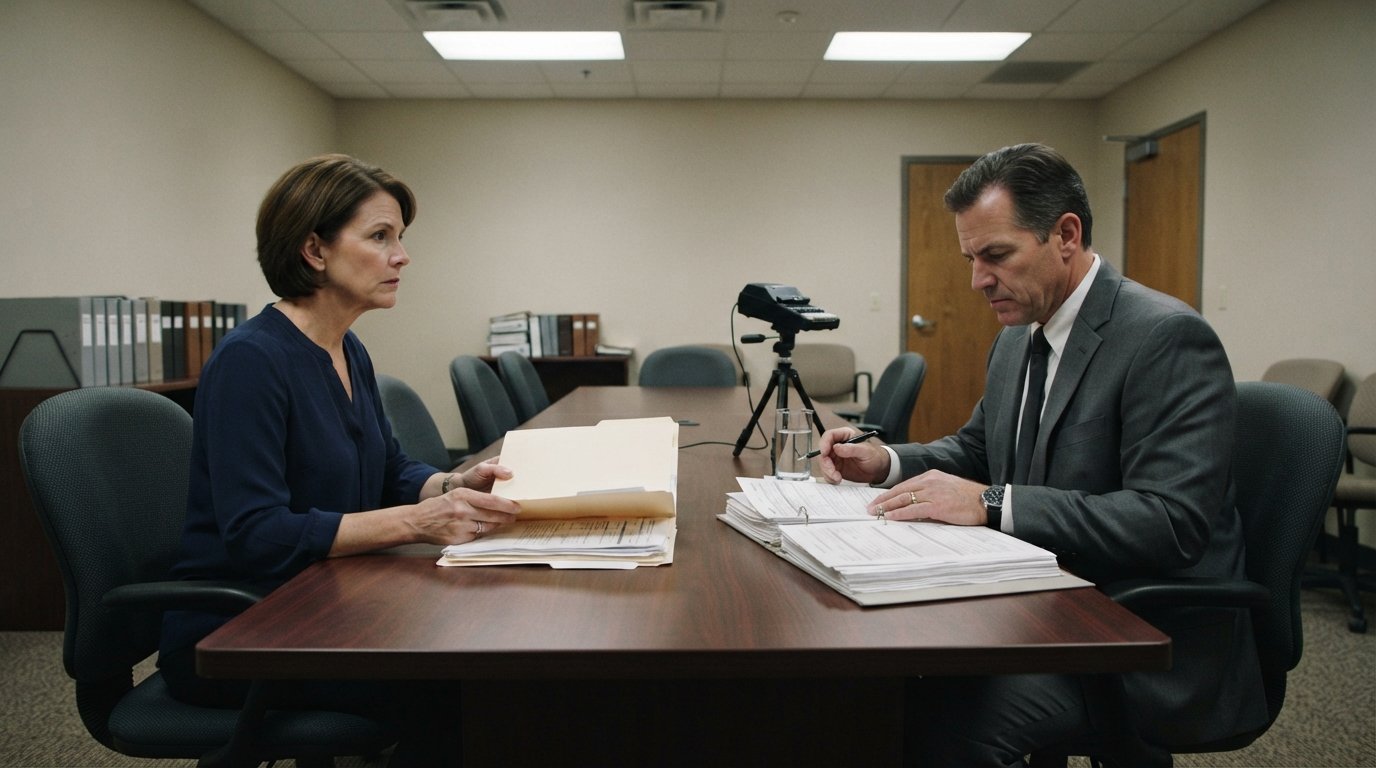
The meeting of creditors is a required hearing in every Chapter 7 bankruptcy case. It is mandated by Section 341 of the Bankruptcy Code, which is why it is commonly called the 341 meeting. A trustee appointed by the U.S. Trustee Program presides over the meeting. The trustee is not a judge. Instead, the trustee acts as an administrator who reviews your case, verifies your identity and financial disclosures, and determines whether any of your assets can be sold to pay creditors.
Despite the name, creditors rarely attend. In most consumer cases, only the debtor, the debtor's attorney (if represented), and the trustee are present. Occasionally, a creditor may appear to ask about a specific debt, such as a recently purchased vehicle or a large cash advance. But the primary purpose is for the trustee to question you under oath about the information in your bankruptcy petition and schedules.
The meeting usually takes place at a federal building, a courthouse, or a designated meeting room, though some districts now conduct these meetings by telephone or video. You must bring photo identification and proof of your Social Security number. The trustee will place you under oath before asking questions. Your answers become part of the official record and carry the same legal weight as testimony in court.
Why the Trustee Asks These Questions
Understanding the trustee's role helps you answer questions without unnecessary anxiety. The trustee is not your adversary in the way a prosecutor might be. The trustee's job is to ensure the bankruptcy system works as intended: honest debtors receive a fresh start, and non-exempt assets are liquidated to pay creditors when possible. The questions are designed to uncover three things: whether your identity is accurate, whether your financial disclosures are complete and truthful, and whether you have any assets that can be recovered for the bankruptcy estate.
Trustees also look for signs of fraud or abuse. For example, if you transferred property to a family member shortly before filing, the trustee may ask about that transfer to determine whether it can be reversed. If you recently repaid a loan to a friend or relative, the trustee may investigate whether that payment constitutes a preferential transfer that should be returned to the estate. These questions are standard and do not necessarily mean you did anything wrong.
In many cases, the trustee's questions are routine and follow a predictable pattern. The trustee has already reviewed your petition and schedules before the meeting. The questions confirm the information on paper and give you a chance to explain any unusual circumstances. If your case is a no-asset case, meaning you have no property that can be sold to pay creditors, the meeting may be brief and uneventful.
Standard Questions the Trustee Will Ask
Most trustees begin with a set of standard questions that cover your identity, your understanding of the bankruptcy process, and the accuracy of your filings. These questions are not designed to trick you. They are designed to create a clear record that you have reviewed your documents and are testifying truthfully. The following list covers the most common questions you should expect.
- State your name and current address for the record.
- Did you review the bankruptcy petition and schedules before they were filed?
- Are all the signatures on the documents yours?
- Is the information in the petition and schedules true and correct to the best of your knowledge?
- Have you filed bankruptcy before, and if so, when?
- Did you list all of your assets and all of your debts?
- Have you transferred, sold, or given away any property in the last two years?
- Have you repaid any loans to family members or friends in the last year?
These questions establish the foundation of your testimony. If you answer yes to reviewing your petition, you are confirming that you understand its contents. If you discover an error during the meeting, you should tell the trustee immediately rather than guessing. Trustees appreciate honesty and often allow debtors to correct minor mistakes through amended schedules.
The question about prior bankruptcies matters because the bankruptcy code limits how often you can receive a discharge. If you received a Chapter 7 discharge within the last eight years, you may not be eligible for another discharge in this case. The trustee will ask about the date of any prior filing to confirm eligibility.
Questions About Your Income and Expenses
Your income and expenses are central to the means test, which determines whether you qualify for Chapter 7 or must file under Chapter 13 instead. The trustee will ask about your current employment, your sources of income, and whether your income has changed since you filed. You should be prepared to explain any significant fluctuations, such as a recent job loss, a reduction in hours, or a new source of income.
Common questions include whether you expect to receive a tax refund, whether you have received an inheritance or life insurance payout, and whether anyone contributes to your household expenses. If you are married but filing alone, the trustee may ask about your spouse's income to assess your household budget. These questions are not intended to embarrass you; they help the trustee determine whether you have disposable income that could be used to pay creditors.
Expense questions are equally important. The trustee may ask whether your listed expenses are accurate and whether you have any expenses that are not reflected in your schedules. For example, if you recently took on a new car payment or started paying for childcare, you should disclose that information. Undisclosed expenses can raise questions about whether your budget is realistic.
Questions About Your Assets and Property
The trustee's primary interest is in your assets. Under Chapter 7, the trustee can sell non-exempt property and distribute the proceeds to creditors. Most consumer debtors have few or no non-exempt assets, which is why the vast majority of Chapter 7 cases are no-asset cases. However, the trustee will still ask detailed questions about your property to confirm that nothing was omitted.
You should expect questions about real estate, vehicles, bank accounts, retirement accounts, and personal property. The trustee may ask whether you own any property that is not listed in your schedules, whether you have any claims against another party (such as a personal injury claim), and whether you are entitled to any future payments, such as a bonus or commission. If you own a home, the trustee will ask about its value, the amount of any mortgage, and whether you have claimed a homestead exemption.
Retirement accounts are often exempt, but the trustee may still ask about them to confirm their status. If you have recently withdrawn money from a retirement account, the trustee may ask how you used those funds. Similarly, if you have a bank account with a balance that seems unusually high, the trustee may ask about the source of the funds and whether they are needed for basic living expenses.
Questions About Recent Financial Transactions
Trustees pay close attention to financial transactions that occurred before you filed. The bankruptcy code allows the trustee to recover certain payments or transfers made within specific time frames, known as the lookback period. For example, if you sold a car to a family member for less than its fair market value within two years before filing, the trustee may investigate whether that transfer can be undone.
Common questions in this category include whether you have transferred any property to anyone in the last two years, whether you have repaid any loans to friends or family in the last year, and whether you have made any large purchases or cash advances on your credit cards in the last ninety days. The trustee may also ask whether you have closed any bank accounts or sold any assets recently.
If you have made transactions that could be questioned, it is best to disclose them upfront and explain the circumstances. For example, if you repaid a loan to your parents, you can explain that it was a bona fide debt and that you were trying to do the right thing. The trustee may still seek to recover the payment, but your honesty will work in your favor.
How to Prepare for the Meeting
Preparation is the best way to reduce stress and avoid mistakes. Start by reviewing your bankruptcy petition and schedules carefully. Make sure you understand every entry and can explain any unusual items. Gather the documents the trustee requested, which typically include your photo ID, Social Security card, recent pay stubs, bank statements, and tax returns. If you are unsure what to bring, contact your attorney or the trustee's office for a list.
Practice answering the standard questions out loud. This will help you speak clearly and confidently during the meeting. Avoid memorizing a script, but do think about how you will explain any recent job changes, large transactions, or unusual expenses. If you are filing with an attorney, your attorney will typically meet with you before the hearing to review your answers and prepare you for the trustee's questions.
On the day of the meeting, arrive early and dress appropriately. Bring your documents in an organized folder. When the trustee asks a question, listen carefully and answer directly. Do not volunteer extra information or speculate about things you do not know. If you do not understand a question, ask the trustee to repeat or clarify it. If you need to correct an answer, do so as soon as you realize the mistake.
What Happens After the Meeting
In most cases, the trustee concludes the meeting by stating that the case will be closed as a no-asset case or that further review is needed. If the trustee has no additional questions, you are free to leave. The trustee will file a report with the court, and you will receive your discharge approximately sixty days after the meeting, assuming no creditors object and no other issues arise.
If the trustee needs more information, the meeting may be continued to a later date. This does not necessarily mean something is wrong. It may simply mean the trustee needs additional documents or time to review a particular issue. Your attorney can help you respond to any follow-up requests. In rare cases, the trustee may determine that you have non-exempt assets that can be sold. If that happens, the trustee will negotiate with you and your attorney to determine how those assets will be handled.
If you are facing financial hardship and considering bankruptcy, you do not have to navigate the process alone. CarInjuryAccident.com connects individuals with a network of experienced attorneys who handle Chapter 7 cases and can guide you through every step, from filing to the trustee meeting. If you are also exploring other legal resources, platforms like FormsByLawyers offer tools and information that can help you understand your options. Requesting a free case evaluation is confidential and carries no obligation to hire.
Common Mistakes to Avoid
One of the most common mistakes debtors make is failing to disclose an asset because they believe it is not valuable. Even if you think an item is worthless, it must be listed on your schedules. The trustee will compare your testimony to your paperwork, and omissions can delay your case or raise suspicions. Another mistake is spending money on luxury items or transferring property shortly before filing. These actions can be reversed by the trustee and may jeopardize your discharge.
Debtors also sometimes guess at answers instead of saying they do not know. If you are unsure about a date or amount, it is better to say you do not recall than to provide incorrect information. You can always supplement your answer later. Finally, do not treat the meeting casually. Even though it is short, it is a legal proceeding, and your testimony matters. Taking it seriously and preparing thoroughly will help you avoid unnecessary complications.
The Chapter 7 trustee meeting of creditors is a predictable step in the bankruptcy process. With the right preparation, you can walk in confident and walk out ready to complete your fresh start. If you have questions about your specific situation, speaking with a qualified bankruptcy attorney is the best way to protect your rights and ensure your case goes smoothly.