Insurance Bad Faith Claim After a Lowball Car Accident Offer
A lowball car accident offer may be insurance bad faith. Call 8555452917 for a free case evaluation and protect your right to fair compensation.
By Kaelis Arden
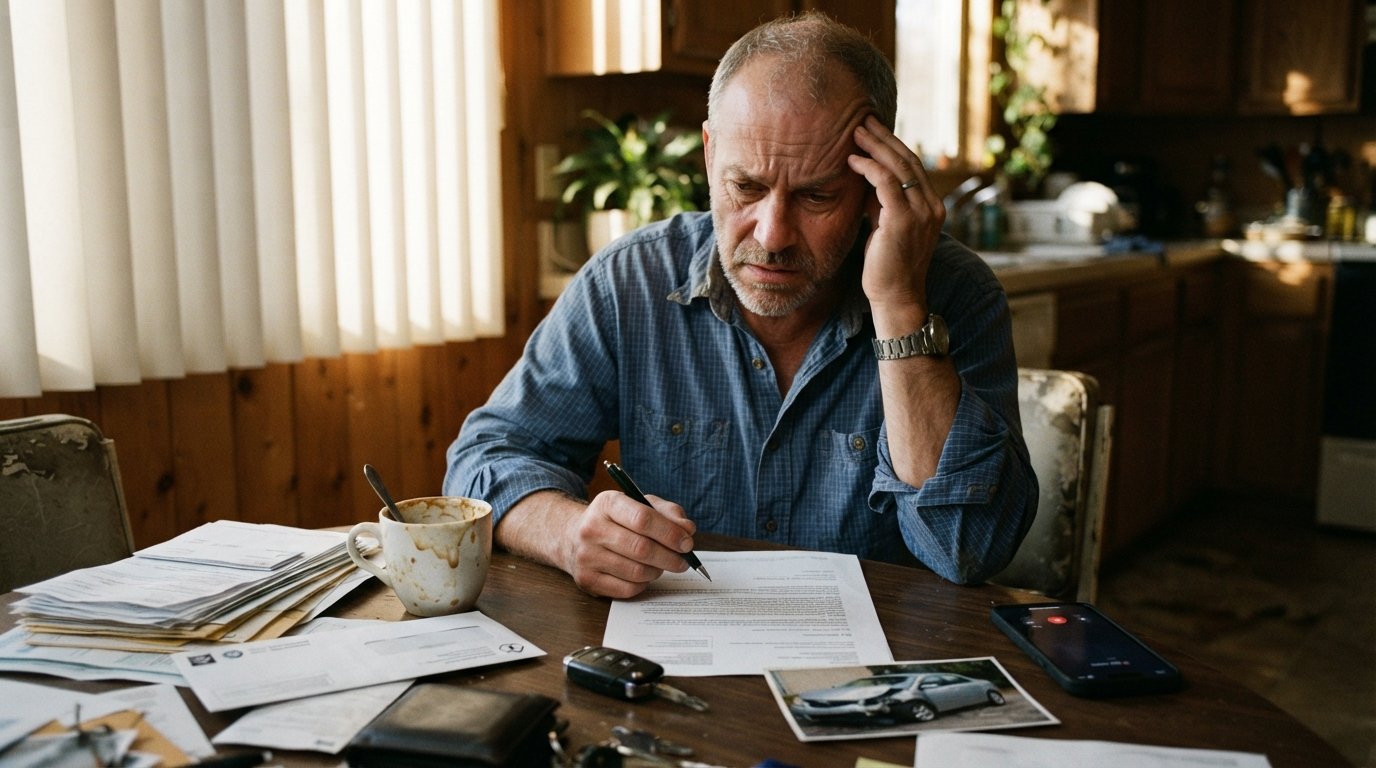
You open the settlement letter expecting a fair number, and instead you see an amount that would not cover your ER visit, let alone weeks of lost income. The adjuster calls it a "final offer" and hints that litigation will take years. What most injured drivers do not realize is that this moment can shift the entire legal landscape in your favor. When an insurer unreasonably delays, denies, or undervalues a valid claim, it may be acting in bad faith, and that opens a separate legal path that goes beyond your original collision.
A lowball offer is often not a mistake. It is a calculated tactic. Insurers know that injured people are stressed, behind on bills, and unsure what their case is worth. They count on you accepting less just to make the pressure stop. Understanding how bad faith works, what evidence matters, and how to respond can mean the difference between a token check and the full compensation you actually deserve.
What a Lowball Offer Really Means in a Car Accident Claim
In a typical car accident claim, you are owed compensation for medical bills, lost wages, pain and suffering, and sometimes future care. A lowball offer is one that ignores or dramatically discounts these categories. The adjuster may claim your injuries were pre-existing, dispute the severity of the crash, or argue that your treatment was unnecessary. None of these conclusions are final, and none of them automatically reduce what you are owed.
What makes a lowball offer legally significant is the context around it. If the insurer has clear liability evidence, complete medical records, and a reasonable basis to know the claim is worth far more, then a token offer can be evidence of bad faith rather than aggressive but lawful negotiation. The key question is not whether the offer is low, but whether it is unreasonable given what the insurer knows.
Many people do not realize how much documentation already exists in their file. Police reports, witness statements, medical imaging, and your own recorded statement all form a record the adjuster can access. When that record supports a serious injury and the offer still comes in near the cost of a fender bender, the gap itself becomes part of your case. If you are still in the early stages and trying to understand the full value of your claim, resources like our guide on car accident insurance settlement maximization can help you see what a reasonable range looks like before you respond.
What Is an Insurance Bad Faith Claim After a Lowball Car Accident Offer?
An insurance bad faith claim after a lowball car accident offer is a separate legal action against the insurer itself, not just the at-fault driver. Every insurance policy carries an implied duty of good faith and fair dealing. That duty means the insurer must investigate promptly, evaluate the claim fairly, communicate honestly, and not put its own financial interests above the legitimate interests of its policyholder or a third-party claimant where the law allows.
Bad faith can occur at any stage. It might look like an outright denial with no explanation, a delay that stretches for months without justification, a refusal to consider medical evidence, or a settlement offer so far below the actual damages that it amounts to coercion. In many states, a pattern of lowball offers combined with ignored evidence is enough to support a claim.
What makes these claims powerful is the potential for damages beyond the original policy limits. Depending on your state, a successful bad faith action may allow you to recover the full value of your underlying claim, emotional distress damages, attorney fees, and in some cases punitive damages designed to punish the insurer. That is why insurers take these allegations seriously, and why a well-documented bad faith claim after a lowball car accident offer can change the entire negotiating dynamic.
Warning Signs That a Lowball Offer Crossed Into Bad Faith
Not every low offer is bad faith. Insurers are allowed to negotiate hard, question damages, and make opening offers below what a case is ultimately worth. The line is crossed when the conduct becomes unreasonable, deceptive, or indifferent to clear evidence. The following signs frequently appear in successful bad faith cases:
- The insurer ignores or refuses to review medical records, imaging, or expert reports that clearly support your injuries.
- The adjuster misrepresents policy limits, coverage terms, or the law in an effort to pressure a quick settlement.
- Offers are made with arbitrary deadlines, such as "accept this today or we withdraw it," without giving you time to consult a lawyer.
- The insurer delays payment or investigation for months while you continue to accrue medical bills and lost wages.
- A reasonable offer is only made after you hire an attorney or file a bad faith claim, suggesting the earlier lowball was strategic rather than honest.
These behaviors matter because they create a paper trail. Emails, recorded calls, offer letters, and claim notes can all be used to show that the insurer knew the claim was worth more and chose to lowball anyway. If you have experienced several of these tactics, your situation may be more than a negotiation problem.
How to Build an Insurance Bad Faith Claim After a Lowball Car Accident Offer
Building a bad faith case requires more than frustration. It requires evidence that the insurer acted unreasonably and that you suffered harm as a result. The process usually follows a predictable sequence, and each step strengthens the next.
- Preserve everything. Keep every letter, email, voicemail, text, and offer. Do not delete recorded statements or call logs. If the adjuster made promises verbally, write down the date, time, and what was said.
- Document your damages completely. Gather medical records, billing statements, wage loss verification, and any future care estimates. A bad faith claim is only as strong as the proof that the lowball offer was unreasonable.
- Send a clear demand with a deadline. A formal demand letter that lays out liability, damages, and the legal consequences of bad faith gives the insurer a final chance to correct course. Many cases settle here because the insurer realizes the exposure is real.
- File the bad faith action if the insurer still refuses. This is typically done alongside or after the underlying injury claim. An attorney can determine whether your state allows first-party or third-party bad faith claims and what damages are available.
Timing is critical. Every state has statutes of limitation for both the underlying injury claim and the bad faith claim, and they do not always run on the same schedule. Waiting too long can eliminate your right to pursue the insurer for its conduct. An experienced attorney can map out both timelines and make sure nothing is lost.
Why Insurers Lowball and What They Hope You Will Do
Insurers lowball because it works. A significant percentage of injured people accept the first or second offer simply because they do not know the true value of their case or they fear a long legal fight. The insurer's math is simple: pay as little as possible, as late as possible, and count on exhaustion to close the file.
They also know that bad faith claims are expensive and embarrassing. A finding of bad faith can trigger regulatory scrutiny, damage the insurer's reputation, and expose it to damages far beyond the original policy. That is why a credible bad faith allegation often produces a dramatically better settlement than continued negotiation over the same low offer. The insurer is no longer just weighing your injuries; it is weighing its own legal exposure.
This is also why you should never assume the first offer is the best you can get. A lowball offer is frequently a starting position, not a final valuation. The difference between accepting it and challenging it can be tens of thousands of dollars, especially in cases involving surgery, permanent injury, or long-term rehabilitation.
The Role of an Attorney in a Bad Faith Claim After a Lowball Car Accident Offer
Bad faith law is technical. Each state defines it differently, and the remedies available vary widely. Some states allow third-party claimants to sue an insurer directly for bad faith; others limit those claims to the policyholder. Some require a prior judgment against the at-fault driver before a bad faith claim can proceed. An attorney who handles these cases regularly will know exactly which path applies to you.
An attorney also brings leverage. Insurers track which law firms actually file bad faith actions and which ones only send demand letters. When your lawyer has a track record of litigating these claims, the adjuster's calculus changes. The file gets escalated, the reserve goes up, and the offers become realistic.
Beyond the legal mechanics, representation removes the emotional burden. You should not have to argue with an adjuster while recovering from injuries. A lawyer handles the calls, the records requests, the deadlines, and the negotiations so you can focus on healing. If you are still deciding whether to hire counsel, a free case evaluation through CarInjuryAccident.com can connect you with participating attorneys in your state who handle bad faith and personal injury claims, with no obligation to hire.
Damages Available Beyond the Original Policy Limits
One of the most misunderstood aspects of bad faith is that it can unlock money that the at-fault driver's policy alone would never provide. If the at-fault driver carried only a minimum policy, that limit may be far less than your actual damages. A bad faith claim against your own insurer or the other driver's insurer can potentially reach beyond that cap.
Depending on your jurisdiction, recoverable damages may include the full amount of the underlying judgment, consequential damages such as additional medical bills caused by the delay, emotional distress, attorney fees, and punitive damages. Punitive damages are not available everywhere, but where they are, they can be substantial and are specifically designed to deter the insurer from repeating the conduct.
This is why documentation of the delay and the lowball offer matters so much. If you can show that the insurer's conduct forced you into debt, foreclosure, or delayed treatment, those harms become part of your damages. The stronger the record, the more pressure the insurer faces to resolve the case at a realistic number.
For people who need help organizing legal documents or connecting with the right professional, resources like FormsByLawyers legal resources can be a useful starting point. Having your paperwork in order before you speak with an attorney makes the initial consultation more productive and helps your lawyer move faster.
Common Mistakes That Weaken a Bad Faith Claim
The strongest bad faith cases are built on clean facts and clear evidence. Unfortunately, some injured people unintentionally undermine their own position before they ever consult a lawyer. The most common mistakes include:
- Accepting a lowball settlement and signing a release before understanding the full extent of injuries.
- Giving a recorded statement to the adjuster without legal guidance, especially early in treatment.
- Waiting months or years to report the injury or file the claim, which gives the insurer a delay defense.
- Failing to keep copies of medical records, bills, and correspondence with the insurer.
- Posting details about the accident or your recovery on social media where the insurer can find them.
Each of these mistakes can be used to argue that the insurer's low offer was reasonable because the claim itself was uncertain. Avoiding them keeps the focus where it belongs: on the insurer's conduct, not on gaps in your own case.
What to Do Right Now If You Have a Lowball Offer
You do not have to accept a lowball offer, and you do not have to fight alone. The first step is to stop negotiating until you understand the true value of your claim and whether bad faith is in play. Do not sign anything, do not cash any check that says "final payment," and do not let a deadline pressure you into a decision you will regret.
Instead, gather your documents, write down the timeline of what the insurer has said and done, and get a professional evaluation. A bad faith claim after a lowball car accident offer is not just about getting more money; it is about holding an insurer accountable for breaking its legal duty to treat you fairly. With the right evidence and the right representation, a lowball offer can become the turning point in your case rather than the end of it.