MedPay Claims After a Car Accident: Your Medical Bills Covered
MedPay covers accident medical bills regardless of fault. Understand your claim and recovery options. Call (855)-545-2917 for a free legal evaluation.
By Draven Nyro
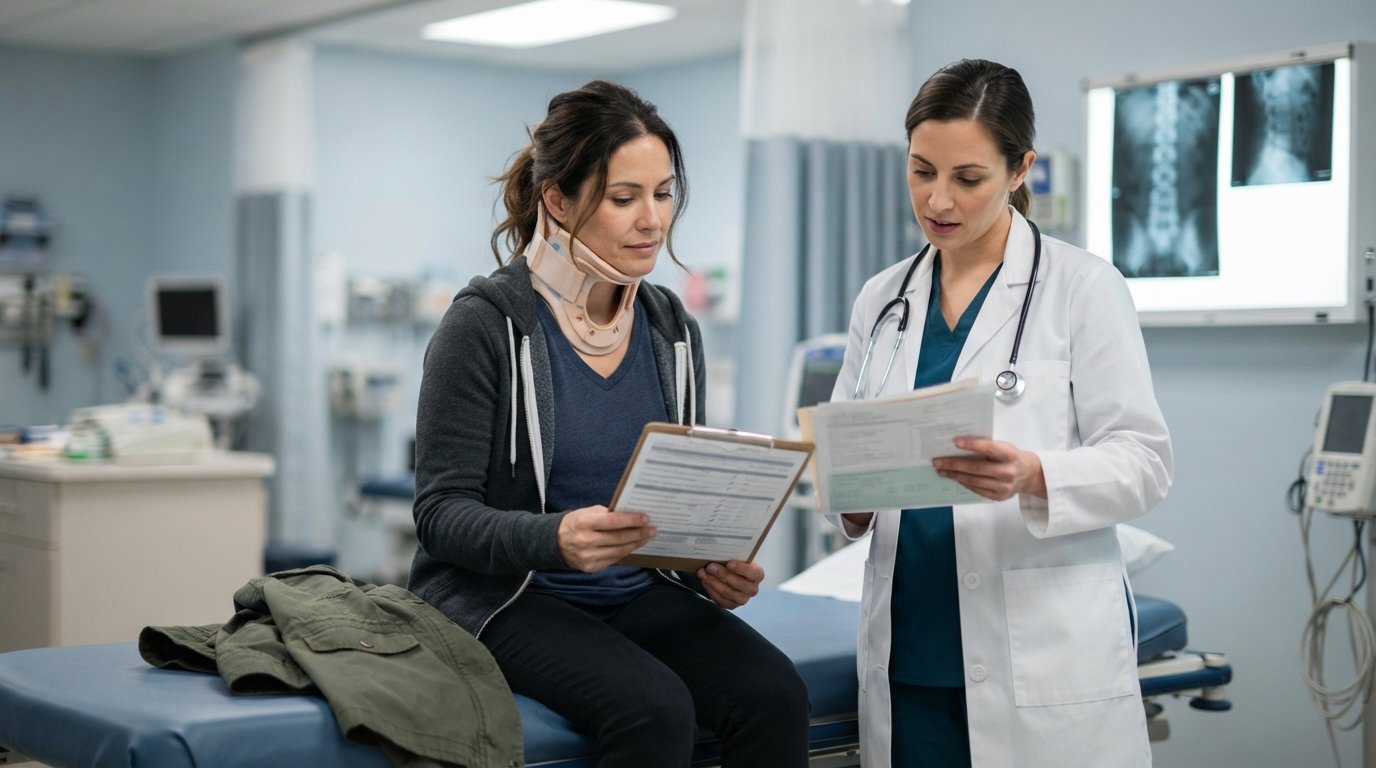
You are sitting in the emergency room after a car accident, staring at a clipboard full of insurance questions. Your neck hurts, your car is likely totaled, and the last thing you need is a financial surprise. This is where medical payment coverage, often called MedPay, can offer immediate relief. MedPay is an optional auto insurance coverage that pays for medical expenses for you and your passengers after a crash, regardless of who caused the accident. It can cover emergency room visits, ambulance rides, X-rays, and follow-up care, up to your policy limit. Understanding how to file a medical payment coverage MedPay claim after a car accident is one of the smartest steps you can take to protect your health and your wallet while the fault investigation unfolds.
What Is MedPay and How Does It Work?
Medical payment coverage is a no-fault benefit attached to your auto insurance policy. When you or your passengers are injured in a car accident, MedPay pays for reasonable and necessary medical treatment, up to the limit you purchased. The key advantage is that MedPay does not wait for a liability determination. Even if the other driver was at fault, or if fault is still being disputed, your MedPay coverage can kick in immediately to cover medical bills. This is different from liability coverage, which belongs to the at-fault driver and pays you only after fault is established and a claim is settled or won.
MedPay typically covers a range of medical services, including:
- Emergency room and hospital visits
- Ambulance and emergency transportation
- Doctor and specialist visits
- X-rays, MRI, and other diagnostic imaging
- Chiropractic care and physical therapy
- Prosthetic devices and some dental care resulting from the accident
Filing a MedPay claim is usually straightforward. You notify your insurer of the accident, provide the medical bills and records related to the crash, and the insurer pays the bills up to your policy limit. You do not need to prove another driver was at fault to access MedPay. This is why it is often called "no-fault" medical coverage. However, MedPay is not unlimited, and it does not cover everything. Understanding its limits and how it interacts with other insurance is essential to making the most of your claim.
MedPay vs. Liability and Uninsured Motorist Coverage
To navigate a MedPay claim effectively, it helps to understand how it differs from other types of auto insurance coverage. Liability coverage is the portion of an at-fault driver's policy that pays for injuries and property damage they cause to others. If another driver hits you, their liability coverage should eventually pay for your medical bills, lost wages, and pain and suffering. But liability claims can take months or longer to resolve, and the at-fault driver's insurer may dispute fault or the extent of your injuries. MedPay, by contrast, pays promptly and without regard to fault.
Uninsured motorist (UM) and underinsured motorist (UIM) coverage are also designed to help when the at-fault driver lacks adequate insurance. UM covers you if you are hit by a driver with no insurance, while UIM covers you if the at-fault driver's policy limits are too low to cover your damages. Both UM and UIM are fault-based in the sense that they step into the shoes of the at-fault driver's liability coverage. They typically pay for a broader range of damages, including pain and suffering, but they can also involve delays and proof of fault. MedPay, on the other hand, is strictly for medical expenses and pays quickly, but it does not compensate you for pain and suffering or lost wages.
Another key difference is repayment. MedPay benefits are often subject to reimbursement from a later liability settlement, while UM/UIM benefits may also be subject to reimbursement depending on your policy and state law. Health insurance also typically seeks reimbursement from a settlement. Understanding these subrogation rights is crucial because it affects how much of your settlement you ultimately keep. The interplay between MedPay, liability, UM/UIM, and health insurance can be complex, which is why many accident victims consult with a personal injury attorney to sort out the best strategy.
Do You Have to Repay MedPay from a Settlement?
One of the most common questions about MedPay is whether you must repay your insurer if you later receive a settlement from the at-fault driver. The answer depends on your policy language and the laws of your state. Many MedPay policies include a subrogation clause, which gives the insurer the right to recover the amounts it paid from any settlement you obtain from a third party. In practice, this means that if your MedPay insurer pays $5,000 in medical bills and you later settle with the at-fault driver for $20,000, your MedPay insurer may claim reimbursement of that $5,000 from your settlement.
However, not all MedPay policies are the same. Some states prohibit MedPay insurers from seeking reimbursement in certain circumstances, or they limit subrogation rights. Some policies waive subrogation entirely, meaning you do not have to repay the MedPay benefits from a later settlement. It is essential to read your policy and understand your state's rules. If you are unsure, an attorney can review your policy and explain your obligations. Failing to account for MedPay reimbursement can lead to unpleasant surprises when you receive your settlement funds.
Additionally, MedPay subrogation can affect your negotiation strategy. If your MedPay insurer has a right to reimbursement, your personal injury attorney will need to address that lien during settlement negotiations. Sometimes the attorney can negotiate the lien down, reducing the amount you owe. In other cases, the MedPay insurer may agree to waive or reduce its claim to facilitate a settlement. Understanding these dynamics is part of maximizing your overall recovery. It is also important to note that MedPay is not the only lien that can attach to your settlement; health insurers and medical providers may also assert liens, which can further complicate the process.
Coordinating MedPay with Health Insurance and Hospital Liens
When you have both MedPay and health insurance, the order in which they pay can matter. In many cases, health insurance is primary and MedPay is secondary, meaning your health insurer pays first and MedPay covers remaining out-of-pocket costs like co-pays and deductibles. But some policies require MedPay to be primary, especially if your health insurance is an HMO or has restrictions. The coordination of benefits provision in your policies will dictate the order. Failing to coordinate properly can result in denied claims or delays in payment.
Hospitals and medical providers often place liens on personal injury claims to ensure they get paid. A hospital lien gives the provider a right to be paid from any settlement or judgment you receive. If you use MedPay to pay hospital bills, the hospital may still assert a lien if MedPay does not cover the full amount. This can create a conflict: MedPay pays part of the bill, but the hospital wants to preserve its lien for the remainder. In some cases, using MedPay can actually reduce the lien amount because the hospital has been partially paid. However, you need to ensure that the hospital does not double-dip by collecting from both MedPay and your settlement.
To avoid problems, keep meticulous records of all medical bills and payments. Notify your health insurer and MedPay insurer of the accident promptly. If you receive a lien notice from a hospital, do not ignore it. An attorney can help you negotiate with lienholders and ensure that liens are properly satisfied from the settlement. They can also help you understand whether MedPay should be used to pay a particular bill or whether it is better to let health insurance handle it. The goal is to maximize your recovery while ensuring all providers are paid fairly.
Limits, Exclusions, and Stacking Across Policies
MedPay coverage comes with limits, typically ranging from $1,000 to $10,000 per person, though higher limits are available. The limit is the maximum amount your insurer will pay for medical expenses per accident or per person, depending on the policy. If your medical bills exceed the MedPay limit, you will need to rely on health insurance, liability coverage, or pay out of pocket. Some policies also have a per-accident limit that caps the total MedPay payout for all injured persons in your vehicle.
Exclusions are also important. MedPay generally does not cover:
- Injuries sustained while committing a felony or while fleeing a crime scene
- Injuries from intentional acts
- Medical expenses not deemed reasonable and necessary
- Treatment unrelated to the accident
- Injuries sustained while using a vehicle for business purposes without proper coverage
Stacking is another concept that can increase your available MedPay benefits. Stacking allows you to combine MedPay limits from multiple policies, such as your auto policy and a policy covering a family member's vehicle. Not all states allow stacking, and some policies include anti-stacking clauses. If you have multiple vehicles on your policy, some insurers offer stacked MedPay coverage for an additional premium. Understanding whether stacking applies to your situation can significantly affect the amount of medical coverage available.
If you are unsure about your MedPay limits or exclusions, review your policy declarations page. It will show your MedPay limit and any endorsements. If you have questions, your insurance agent or an attorney can help clarify. Remember that MedPay is an optional coverage, so you must have purchased it for it to apply. If you did not purchase MedPay, you may still have access to other coverage, such as PIP (personal injury protection) in no-fault states, which is similar but often broader.
When a Coverage Dispute Needs Attorney Involvement
Most MedPay claims are paid without controversy, but disputes can arise. Common issues include the insurer denying coverage based on a pre-existing condition, disputing whether treatment was related to the accident, or refusing to pay bills it considers excessive. If your MedPay claim is denied or delayed, you may need to appeal the decision or file a complaint with your state insurance department. In some cases, an attorney can help you challenge the denial and recover the benefits you are owed.
Coverage disputes can also arise when multiple insurers are involved. For example, if you have MedPay through your auto policy and health insurance through your employer, the two insurers may disagree about which is primary. This can lead to delays and denied claims. An attorney can help you navigate the coordination of benefits and ensure that both insurers meet their obligations. They can also help you understand your rights under state law, including any prompt-payment statutes that require insurers to pay claims within a certain timeframe.
If you are facing a coverage dispute, consider the following steps:
- Review your policy and the denial letter carefully to understand the reason for denial.
- Gather all medical records and bills that support your claim.
- Submit a written appeal to the insurer, including any additional evidence.
- Contact your state insurance department to file a complaint if the insurer does not respond fairly.
- Consult with a personal injury attorney who can evaluate your case and potentially file a bad faith claim.
Even when there is no dispute, an attorney can help you maximize your MedPay benefits and coordinate them with other coverage. For example, an attorney can ensure that MedPay is used to pay medical bills that would otherwise be subject to a hospital lien, reducing the lien amount. They can also help you avoid mistakes that could jeopardize your claim, such as missing deadlines or failing to disclose all medical providers. If you are unsure whether you need an attorney, consider a free consultation. Many personal injury attorneys offer free case evaluations and work on a contingency fee basis, meaning you pay nothing unless they recover compensation for you.
For those interested in learning more about the claims process in general, our article on filing a claim after a car accident provides additional guidance. Additionally, if you are an attorney or law firm looking to connect with potential clients, AttorneyLeads offers a platform for exclusive, pre-screened legal leads. Always remember that CarInjuryAccident.com is not a law firm and does not provide legal advice; it is a resource to connect you with qualified attorneys.
In the aftermath of a car accident, MedPay can be a financial lifeline. By understanding how it works, how it interacts with other insurance, and what to do if a dispute arises, you can make informed decisions and focus on your recovery. If you have questions about your specific situation, consider reaching out to a personal injury attorney who can guide you through the process and protect your rights.