Stop Foreclosure: Loan Modification Before Bankruptcy
Prevent foreclosure with loan modification before bankruptcy. Call (855)-545-2917 to speak with an attorney about your options.
By Calix Rowan
Falling behind on mortgage payments is one of the most stressful financial situations a homeowner can face. The threat of foreclosure looms, and every letter from the lender feels like a countdown. Before you consider bankruptcy as your only option, there is a powerful alternative that many homeowners overlook: loan modification. By negotiating new terms with your lender, you can often cure the default and keep your home without the long-term damage of bankruptcy. This guide explains how loan modification works, how it compares to bankruptcy, and the critical steps to take when a notice of sale is already on the horizon.
How Loan Modification and Forbearance Work
A loan modification permanently changes the terms of your mortgage to make payments affordable. The goal is to reduce your monthly obligation to a level you can sustain, typically by lowering the interest rate, extending the loan term, or rolling past-due amounts into the new balance. Lenders are often willing to modify loans because foreclosure is expensive for them, and a performing loan is more valuable than a distressed property. The process requires a detailed application, proof of hardship, and patience, but it can stop the foreclosure clock while the review is underway.
Forbearance, on the other hand, is a temporary pause or reduction of payments. It is usually granted for a specific period, such as three to six months, and the missed payments must be repaid later, often through a repayment plan or a modification. Forbearance can provide immediate relief, but it is not a permanent fix. Many homeowners use forbearance as a bridge while they apply for a modification. The key difference is that modification addresses the root cause of the delinquency, while forbearance only delays the reckoning.
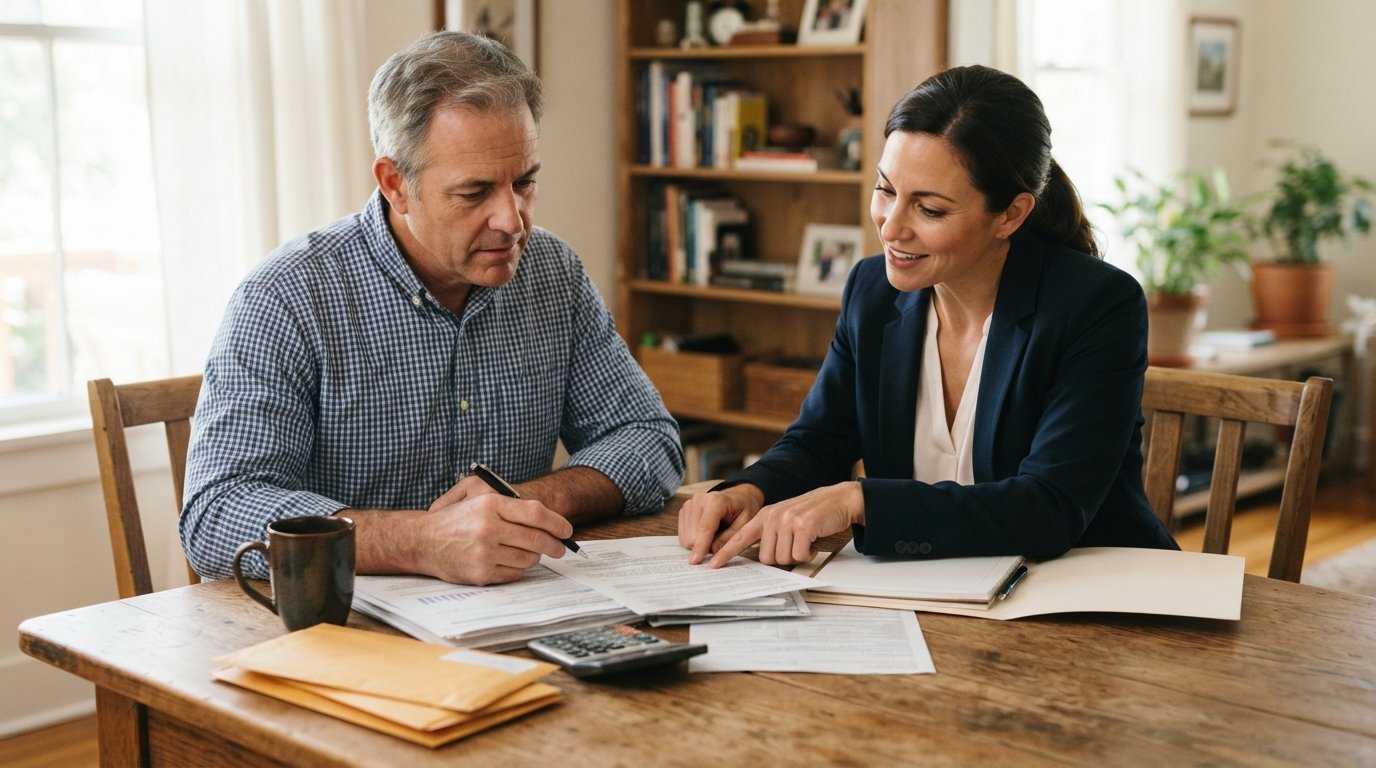
To start either process, you will need to contact your lender's loss mitigation department and submit a complete application. The typical requirements include:
- A hardship letter explaining why you fell behind (job loss, medical emergency, divorce, etc.)
- Recent pay stubs, tax returns, and bank statements to verify income
- A monthly budget and financial worksheet
- Proof of any other income sources (Social Security, disability, child support)
Lenders evaluate these documents using investor guidelines and federal programs. The process can take weeks or months, so starting early is crucial. If you are already facing a foreclosure sale date, you must act immediately. An experienced attorney can help you navigate the paperwork and communicate with the lender to ensure your application is complete and your rights are protected. CarInjuryAccident.com connects homeowners with attorneys who handle foreclosure defense and loan modification, offering free case evaluations to help you understand your options.
Chapter 13 Cure and Maintain Versus Chapter 7 Timing
Bankruptcy is another tool to stop foreclosure, but it works very differently from loan modification. Chapter 13 bankruptcy allows you to cure the default over three to five years while maintaining your regular mortgage payments. This is known as "cure and maintain." The bankruptcy court protects you from collection and foreclosure during the repayment plan, giving you time to catch up. However, Chapter 13 requires a steady income and a feasible budget, and it carries long-term credit consequences. It is often a last resort when modification fails or when you have multiple debts that need restructuring.
Chapter 7 bankruptcy, by contrast, does not offer a cure mechanism for secured debts like a mortgage. It can discharge unsecured debts and may delay foreclosure temporarily due to the automatic stay, but the stay is short-lived. If you are behind on your mortgage, Chapter 7 will not save your home unless you can catch up quickly or negotiate a reaffirmation agreement. In many cases, Chapter 7 is better suited for homeowners who are willing to let the property go and need relief from other debts. The timing is critical: filing Chapter 7 immediately before a foreclosure sale can buy you a few weeks, but it does not provide a long-term solution.
The decision between loan modification and bankruptcy depends on your financial situation, your goals, and the stage of foreclosure. Modification is generally the preferred first step because it preserves your credit and avoids the stigma of bankruptcy. Bankruptcy should be considered when modification is not viable or when your overall debt load is unmanageable. A qualified attorney can help you compare the outcomes and choose the path that best protects your home and your financial future. For a deeper look at how bankruptcy affects different types of debt, see our guide on student loan debt bankruptcy options.
Protecting Homestead Exemptions
Homestead exemptions protect a portion of your home equity from creditors in bankruptcy and from certain judgments. The protection varies significantly by state, with some states offering unlimited homestead protection and others capping it at a specific dollar amount. In a Chapter 7 bankruptcy, the homestead exemption determines whether you can keep your home if you are current on payments. In Chapter 13, the exemption affects how much you must pay to unsecured creditors. Understanding your state's exemption is essential before filing, as it can influence whether bankruptcy is a viable strategy for keeping your home.
Loan modification does not implicate homestead exemptions directly because it is a contractual agreement with your lender, not a court proceeding. However, if you are considering bankruptcy as a fallback, you should consult an attorney to confirm your exemption amount and how it applies to your situation. Some states allow married couples to double the exemption, and others have residency requirements that can affect eligibility. A mistake in claiming the exemption can cost you your home, so professional guidance is critical.
Timeline Risks Once a Notice of Sale Is Filed
Once a notice of sale is filed, the foreclosure process moves quickly. The timeline varies by state, but in many jurisdictions, the sale can occur within 30 to 120 days. This is the most dangerous period for homeowners because the lender is not obligated to pause the sale just because you have applied for a loan modification. However, many states and federal programs require lenders to review a complete modification application before proceeding with foreclosure. The key is to submit a complete application as early as possible and to follow up diligently.
If a sale date is scheduled, you may need to seek an emergency injunction or file bankruptcy to stop the sale. An attorney can help you determine whether the lender has violated any laws or regulations, which could provide grounds for a temporary restraining order. Time is of the essence: once the sale occurs, reversing it is extremely difficult. Homeowners should not wait until the last minute to seek help.
When a Short Sale or Deed-in-Lieu Makes Sense
If loan modification is not approved and bankruptcy is not the right fit, a short sale or deed-in-lieu of foreclosure may be the best way to avoid a formal foreclosure on your credit report. A short sale involves selling the home for less than the outstanding mortgage balance, with the lender agreeing to accept the proceeds as full satisfaction of the debt. A deed-in-lieu is a voluntary transfer of the property to the lender in exchange for release from the mortgage obligation. Both options are less damaging than foreclosure and can help you move on with your life.
These alternatives are most appropriate when you can no longer afford the home and do not qualify for a modification. They require lender approval and can take months to complete, so they are not quick fixes. However, they can provide a dignified exit and may be preferable to a lengthy bankruptcy process. An attorney can negotiate with the lender and ensure that any deficiency judgment is waived.
For homeowners who are also dealing with other legal issues, such as personal injury or divorce, the stress of foreclosure can be overwhelming. CarInjuryAccident.com offers a network of attorneys across multiple practice areas, including bankruptcy and foreclosure defense. If you are considering bankruptcy as part of a broader debt relief strategy, you may also want to explore our resource on attorney leads for legal professionals seeking to connect with clients in need.
The most important step is to act before the situation becomes dire. Loan modification, forbearance, and bankruptcy all have their place, but timing and professional guidance are critical. By understanding your options and seeking help early, you can protect your home and your financial future.