Whiplash Injury Claim: Proving Severity and Damages
Build a whiplash injury claim proving severity and damages with the right medical records and symptom logs. Call (855)-545-2917 for a free case review.
By Draven Nyro
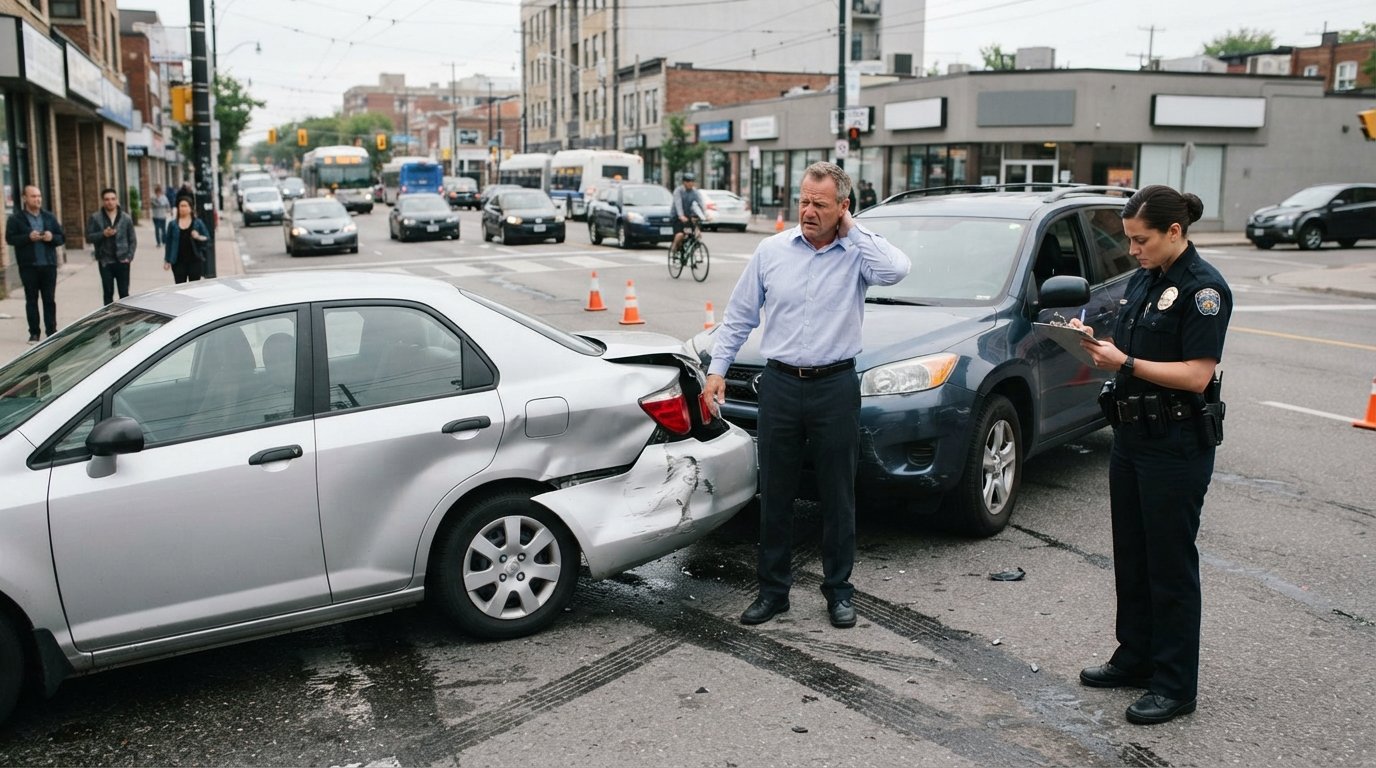
Your neck hurts, the other driver's insurer is already calling, and you have no visible cast or broken bone to point to. Whiplash is one of the most common car crash injuries in the United States, yet it is also one of the most aggressively disputed. Insurers know that soft tissue injuries can be hard to see on a standard X-ray, and they use that ambiguity to question severity, delay treatment approvals, and push low settlements. If you are trying to build a whiplash injury claim proving severity and damages, the outcome will depend far less on how much pain you feel and far more on how well that pain is documented.
This guide walks through the evidence adjusters actually weigh, the records that separate a credible severe whiplash claim from one that gets minimized, and the point at which professional representation becomes the smartest financial move. The goal is not to teach you to exaggerate. It is to help you translate a real injury into the language and paperwork an insurance company respects.
Why Insurers Dispute Whiplash Injuries So Aggressively
Whiplash is a rapid back-and-forth movement of the neck, most often caused by a rear-end collision. The force stretches muscles, ligaments, and nerves beyond their normal range, producing symptoms that range from mild stiffness to severe pain, headaches, dizziness, numbness, and cognitive fog. According to the Mayo Clinic and the National Highway Traffic Safety Administration, whiplash is reported in a large share of rear-impact crashes, and many victims recover within weeks while others develop chronic pain lasting months or years.
From an adjuster's desk, that spectrum creates an opportunity. A claim file with a vague emergency room note, a few missed physical therapy appointments, and no imaging gives the insurer room to argue the injury was minor, pre-existing, or exaggerated. When an insurer disputes severity, it is usually attacking one of four things: the mechanism of injury, the objectivity of the diagnosis, the consistency of treatment, or the connection between the crash and the symptoms. Your evidence strategy should anticipate each attack.
There is also a structural reason for the skepticism. Whiplash claims are frequent, and a small percentage of them are inflated. Insurers respond by treating every soft tissue claim as suspect until documentation proves otherwise. That is frustrating for honest claimants, but it is the reality of the negotiation table. The claimants who recover fair compensation are the ones who build a file so consistent and complete that the adjuster has little room to argue.
The Medical Evidence That Proves Severity
Medical records are the backbone of any whiplash claim. An adjuster will read them looking for objective findings, a clear diagnosis, a treatment plan, and proof that the treatment was followed. A single emergency room visit that says "neck pain, discharged" is weak. A record that includes imaging, a specialist evaluation, and a documented course of care is strong.
Imaging deserves special attention because whiplash is often described as an injury that does not show up on tests. That is only partly true. X-rays can reveal fractures, dislocations, and degenerative changes that predate the crash. MRI can detect disc herniations, bulges, ligament damage, and spinal cord compression. CT scans help evaluate bony injury. Even when imaging is normal, the ordering of those tests matters: it shows the treating physician took the complaint seriously and ruled out serious structural damage. A normal MRI is not proof of no injury; it is proof that the injury is soft tissue in nature, which is exactly what whiplash is.
Treatment records carry equal weight. They should document the onset of symptoms, the diagnosis (such as cervical strain, cervicalgia, or whiplash-associated disorder), the severity rating, the prescribed course of care, and your response to treatment. If a physician refers you to physical therapy, chiropractic care, or a pain specialist, those notes become part of the same chain of evidence. Gaps in that chain are where claims weaken.
Symptom diaries are frequently underestimated. A daily log that records pain levels, location, limitations (for example, difficulty turning your head to drive), sleep disruption, and medication use creates a timeline that corroborates the medical records. Adjusters are trained to look for consistency between what you told the doctor and what you claim later. A diary makes that consistency visible.
If you are also managing related injuries from the same crash, the documentation principles are similar. Our guide on a back injury car accident claim explains how imaging and treatment history support fair compensation for spinal injuries, and the same logic applies to the neck.
Explaining Delayed Symptoms and Gaps in Care
Two of the most common reasons whiplash claims lose value are delayed symptom onset and gaps in treatment. Insurers treat both as evidence that the injury was not serious or was not caused by the crash. In reality, both have innocent explanations that must be documented early.
Delayed onset is medically normal. Adrenaline and endorphins can mask pain for hours or even days after a collision. Muscle stiffness often peaks 24 to 72 hours later. Many people wake up the next morning unable to turn their head. If you did not go to the emergency room immediately, explain why in your records: you felt fine at the scene, you thought it would pass, you had no one to watch the children, or you were told by a phone nurse to monitor symptoms. A primary care visit within a few days still establishes the link between the crash and the injury.
Gaps in care are more complicated. A gap can occur because of insurance delays, transportation problems, work schedules, or a period when symptoms seemed to improve. Each gap should have a documented reason. If you missed appointments because the insurer delayed authorization, keep the denial letters. If you stopped therapy because you felt better and then relapsed, tell your doctor so the note reflects it. Unexplained gaps invite the argument that you were healed and then returned only when a lawyer got involved.
The strongest files tell a coherent story: crash, symptoms, diagnosis, treatment, compliance, and outcome. When that story has holes, the adjuster fills them with the least favorable interpretation. Your job is to fill them first.
How Whiplash Settlement Values Are Built
There is no fixed price for whiplash. Settlement values are built from economic damages (medical bills, lost wages, out-of-pocket costs) and non-economic damages (pain, suffering, loss of enjoyment of life). Insurers then apply multipliers or software formulas that weigh severity, liability, and documentation quality. A well-documented moderate injury can sometimes outperform a poorly documented severe one.
Treatment history is the strongest predictor of value. A claimant with three months of consistent physical therapy, specialist evaluations, and imaging-supported findings will typically see a higher range than a claimant with one urgent care visit and no follow-up. The table below is illustrative, not a guarantee, and actual values vary by state, liability facts, and policy limits.
- Mild whiplash: symptoms resolve in a few weeks, one or two medical visits, no imaging, limited wage loss.
- Moderate whiplash: symptoms last two to six months, imaging performed, consistent therapy, some work restrictions.
- Severe whiplash: symptoms beyond six months, specialist care, disc or ligament findings, documented limitations, significant wage loss.
- Chronic or complicating factors: pre-existing degeneration aggravated by the crash, nerve involvement, or psychological effects such as anxiety while driving.
Adjusters also look at whether the crash produced significant vehicle damage. Counterintuitively, low-speed collisions can produce serious whiplash because the neck absorbs force even when the bumper does not crush. Do not assume a minor repair bill means a minor injury, but do expect the insurer to raise that argument. Medical evidence and a credible mechanism explanation are your response.
Liability and policy limits cap the theoretical value. If the at-fault driver carries state minimum coverage, even a severe claim may be limited unless uninsured or underinsured motorist coverage applies. That is why a thorough review of all available policies, including your own, is part of building a complete claim.
When a Lowball Offer Means You Need an Attorney
Insurers make initial offers early, often before treatment is complete, because an early low offer is cheap to make and sometimes accepted. A lowball offer on a whiplash claim usually looks like this: medical bills are acknowledged but general damages are minimal, future care is ignored, wage loss is disputed, or the adjuster claims the injury is degenerative and unrelated to the crash.
You should consider bringing in a personal injury attorney when any of the following is true:
- The offer does not cover your current medical bills plus a reasonable amount for pain and suffering.
- The adjuster disputes causation despite consistent medical records.
- You have ongoing symptoms and the insurer refuses to account for future care.
- There is a coverage dispute, an uninsured driver, or a denied claim.
- You are close to the statute of limitations deadline for your state.
An attorney can request the full claim file, obtain a narrative report from your treating physician, retain an accident reconstruction expert if liability is contested, and negotiate from a documented position rather than a verbal one. Most personal injury attorneys work on contingency, meaning you pay nothing upfront and the fee comes from the recovery. That structure makes a consultation low risk even if you are unsure whether you need representation.
If you are comparing options for legal help, platforms such as LawyerOffer provide legal information and attorney referral services for people navigating personal injury and insurance claims in the United States. Whether you use a referral service or contact a local firm directly, ask about contingency fees, case timelines, and who will handle communication with the insurer.
A Practical Checklist for Strengthening Your Claim
Building a strong whiplash file is a series of small, consistent actions. Start with medical care, then organize the paper trail as you go rather than trying to reconstruct it months later. The following steps make the biggest difference in how an adjuster values severity and damages.
- See a doctor within a few days of the crash, even if symptoms seem mild, and describe the collision mechanism clearly.
- Follow the treatment plan and document any reason for missed appointments.
- Keep a daily symptom diary with pain levels, limitations, and medication use.
- Retain all bills, wage statements, and correspondence with the insurer.
- Do not sign a release or accept a quick settlement before treatment is complete or you have consulted an attorney.
Each of these steps reinforces the others. A diary that matches the medical records, records that match the bills, and bills that match the wage loss create a closed loop of evidence. When an adjuster cannot find a contradiction, the negotiating range moves upward.
Whiplash is a real injury with real costs, and the insurance industry knows it. The difference between a minimized claim and a fair one is almost always documentation. Treat your medical care as the priority, treat your records as evidence, and do not let an early offer pressure you into closing a file before you understand what it is worth.