Bankruptcy and Medical Debt From a Car Accident Injury
Medical debt from a car crash can be discharged, but your injury claim may be an asset. Call (855)-545-2917 for a free case review.
By Kaelen Virex
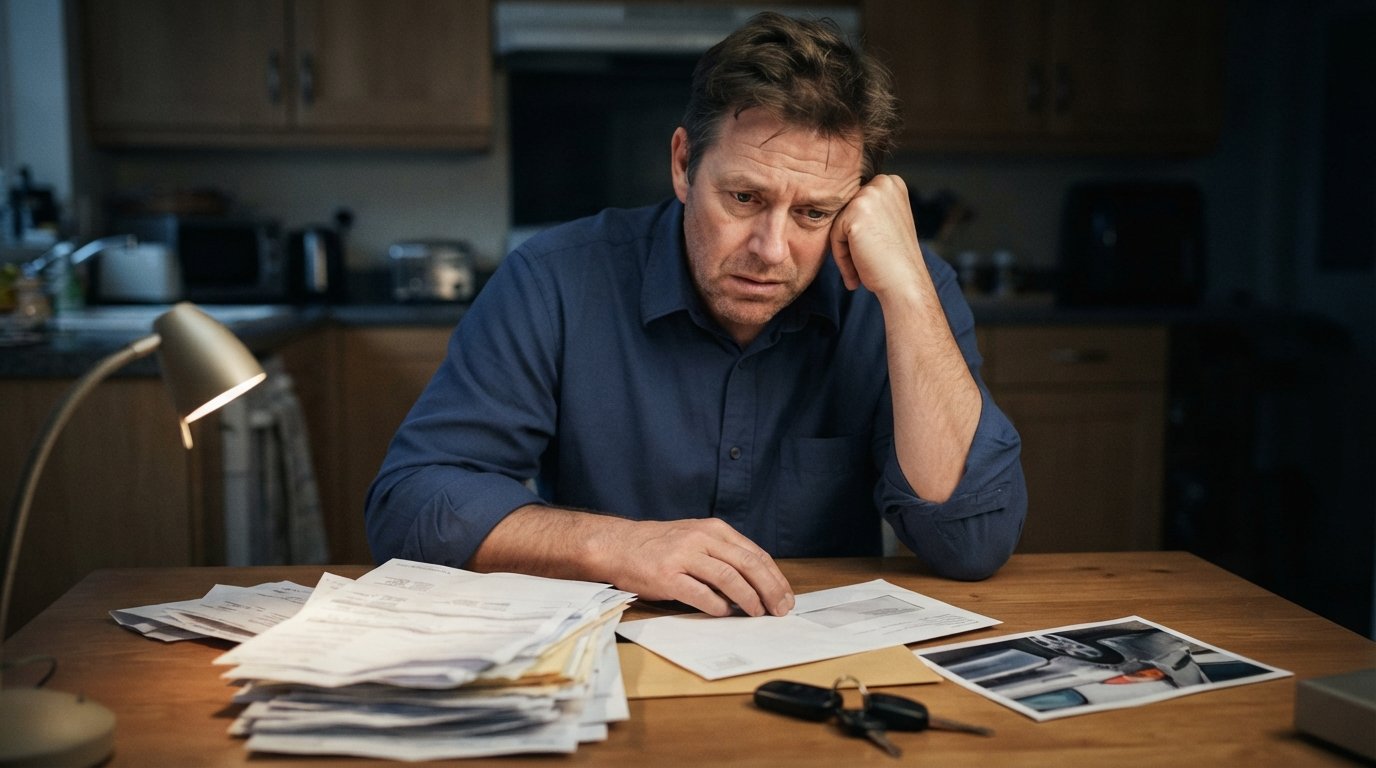
A serious car accident can leave you with injuries, lost wages, and a stack of medical bills that feels impossible to climb out from under. When the at-fault driver's insurance is slow, denies fault, or offers far too little, the financial pressure can push families toward a difficult question: should I file for bankruptcy because of medical debt from a car accident injury? The answer is rarely simple, because the injury claim itself may be an asset that a bankruptcy trustee can see. Understanding how these two legal processes interact, before you sign anything or file any paperwork, can protect both your recovery and your fresh start.
Can Medical Debt From a Crash Be Discharged in Chapter 7?
In most cases, yes. Medical debt is generally treated as an unsecured, nonpriority debt in bankruptcy. That means it is dischargeable in a Chapter 7 case, just like credit card balances and personal loans, assuming the debt is legitimate and you do not commit fraud. Hospital bills, ambulance charges, emergency room fees, surgical costs, physical therapy invoices, and even bills from a chiropractor after a crash typically fall into this category. If you qualify for Chapter 7 under the means test, those bills can be wiped out at the end of the case.
There are important exceptions and wrinkles. Medical debt incurred through fraud, or bills tied to services a provider argues were not medically necessary, can be challenged. More significantly, medical providers sometimes hold liens or file claims against your personal injury case. A hospital may assert a lien on your settlement proceeds under state law, which means the bill follows the money rather than disappearing with the discharge. Whether a lien survives bankruptcy depends on state law and on when the lien was perfected. This is one of the many reasons to speak with an attorney who handles both injury claims and bankruptcy before you decide on a strategy.
Chapter 13 works differently. Instead of wiping out debts immediately, Chapter 13 reorganizes them into a three to five year repayment plan. Medical debt is typically treated as a general unsecured claim, which means it receives whatever percentage of your disposable income the plan provides, and any remaining balance is discharged at the end of the plan. For someone with a steady income and a valuable injury claim, Chapter 13 can be a way to protect assets while still addressing the bills.
Your Injury Settlement Is an Asset in Bankruptcy
This is the point where many accident victims get surprised. A personal injury claim, whether it is still pending or already settled, is property of the bankruptcy estate. When you file, you are required to disclose it. If you are in the middle of litigation, the trustee has the right to step into your shoes, pursue the claim, and distribute the proceeds to your creditors. If you have already received a settlement and it is sitting in a bank account, the trustee may be able to reach it as well.
The good news is that bankruptcy law does not ignore the human side of this. The purpose of the injury claim is to compensate you for pain, suffering, and future medical needs, and the law generally recognizes that some or all of that recovery should stay with you. That is where exemptions come in. Every state has a set of exemptions that protect certain property from creditors, and many states specifically protect personal injury recoveries, at least in part.
Exemptions That May Protect Part of a Personal Injury Recovery
Exemption rules vary dramatically from state to state, and the amounts change over time. Some states protect the entire recovery for personal bodily injury, while others cap it at a specific dollar amount. Some distinguish between compensation for pain and suffering and compensation for lost wages or medical expenses, protecting the former more generously. A few states allow you to choose between state and federal exemptions, which can make a significant difference.
Here is a general framework for how courts and trustees tend to look at the components of an injury recovery:
- Pain and suffering: Frequently protected by bodily injury exemptions, though the dollar cap varies by state.
- Future medical expenses: Often treated as compensation for ongoing injury and may be exempt or partially exempt.
- Lost wages: Sometimes treated as ordinary income replacement and less likely to be fully exempt.
- Punitive damages: Often not exempt or only partially exempt, depending on the state.
- Property damage: Usually treated as replacement for a vehicle or other property and subject to standard property exemptions.
Because the characterization of each dollar matters, you should never assume that filing bankruptcy will simply wipe out the medical bills while leaving the entire settlement untouched. An experienced attorney can review your state's exemption statutes, look at the nature of your injuries, and help you structure the timing of a filing to maximize what you keep.
Timing: When to File Relative to an Open Accident Claim
Timing is often the single most important decision in a case that involves both bankruptcy and medical debt from a car accident injury. Filing too early can hand a valuable claim to a trustee. Filing too late can leave you exposed to creditor collection, wage garnishment, or a lien on the settlement. There is no one-size-fits-all answer, but there are several common scenarios.
- File before the claim is resolved: The trustee takes control of the claim and may settle it. You may still be able to exempt a portion of the proceeds, but you lose control over negotiation and timing. This approach can make sense if the claim is modest and the medical debt is overwhelming.
- Wait until the claim settles, then file: The settlement proceeds become an asset in the bankruptcy. If your state's exemptions cover the amount, you may keep it. If not, the trustee may take the non-exempt portion for creditors.
- File a Chapter 13 while the claim is pending: The claim remains an asset, but you may be able to propose a plan that pays creditors over time while preserving the ability to pursue the injury case. This requires careful coordination with both the injury lawyer and the bankruptcy lawyer.
- Negotiate medical liens before filing: Sometimes the best path is to resolve the hospital liens or reduce the medical bills through negotiation first, then decide whether bankruptcy is still necessary.
Each of these paths has trade-offs. The right one depends on the size of the claim, the amount of the medical debt, the exemptions available in your state, your income, and whether you are facing immediate collection pressure. A free case evaluation through our legal help and attorney matching service can help you understand which path fits your situation before you commit to a filing.
If your injury claim is still open, it is also worth reviewing our guide on car accident injury settlement steps to fair compensation so you understand how the claim itself should be built, independent of the bankruptcy question.
How the Bankruptcy Trustee and Injury Counsel Work Together
When a bankruptcy is filed while an injury claim is pending, the trustee and your personal injury attorney become unlikely partners. The trustee has a duty to maximize the estate for creditors, which means the trustee may want to settle the claim quickly, while your injury lawyer wants to maximize your recovery. These goals are not always aligned, and the tension can affect the outcome of your case.
In practice, the trustee will typically require notice of the claim, may request copies of demand letters and medical records, and may ask to be included in settlement negotiations. Some trustees will allow the injury attorney to continue handling the case, subject to court approval, with the understanding that the proceeds will be turned over to the estate and then distributed according to exemptions and creditor claims. Other trustees prefer to take a more active role. The key is transparency: failing to disclose a personal injury claim in bankruptcy is a serious problem that can lead to denial of discharge or even allegations of fraud.
Coordination also matters on the medical lien side. Hospitals and other providers often file liens against settlement proceeds. Your bankruptcy attorney needs to know about those liens, and your injury attorney needs to understand how the bankruptcy filing affects them. If the liens are discharged or reduced in bankruptcy, that can free up more of the settlement for you. If they survive, they must be paid from the proceeds. Either way, the two attorneys should be communicating, and you should be the one making sure they do.
Practical Steps to Take Before You File
If you are considering bankruptcy because of medical debt from a car accident injury, do not rush. A few deliberate steps can make a major difference in what you keep and what you lose.
First, gather every document related to the accident: the police report, medical records, bills, insurance correspondence, and any demand letters or settlement offers. Second, get a clear picture of your total debt, including the medical bills, and separate the accident-related debt from other obligations. Third, find out what exemptions your state offers for personal injury recoveries, and get a realistic estimate of what your claim is worth. Fourth, talk to both an injury attorney and a bankruptcy attorney, ideally ones who have worked together before, so the strategies do not conflict.
It is also worth understanding that bankruptcy is not the only option. Sometimes medical providers will negotiate a reduced payoff, especially when a settlement is pending. Sometimes the at-fault driver's policy limits are high enough to cover the bills if the claim is pursued aggressively. Sometimes a Chapter 13 plan is a better fit than Chapter 7 because it protects a valuable claim. The point is to make an informed decision rather than a panicked one.
Facing a mountain of medical debt after a crash is overwhelming, but you are not without options. The interaction between bankruptcy and a personal injury claim is complex, and the details of your state's exemptions and your specific injuries will shape the best path forward. Getting advice early, before you sign a settlement release or file a petition, is the surest way to protect both your recovery and your financial future. If you are unsure where to start, a confidential consultation with a qualified attorney can clarify your choices and help you move forward with confidence.