Rideshare Driver Injured in Accident: Workers' Comp or Claim?
Injured as a rideshare driver? Know your workers' comp or claim options. Call (855)-545-2917 for a free case review and protect your recovery.
By Kaelis Arden
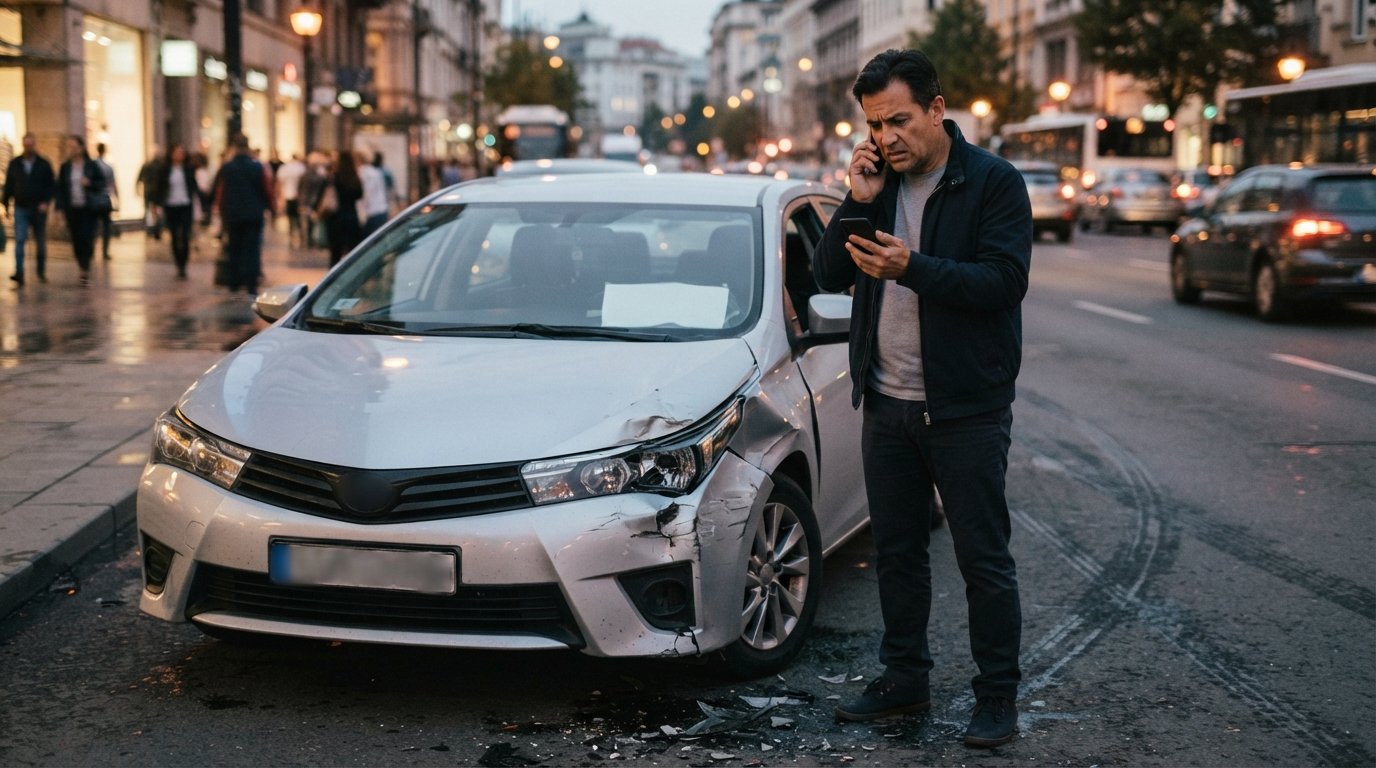
You are a rideshare driver. You spend hours on the road, navigating traffic and passengers. Then, in an instant, a crash changes everything. You are hurt, your car is damaged, and you cannot drive. The first question that races through your mind is: who pays for this? As a rideshare driver injured in an accident, workers compensation or claim options may be available, but the path to recovery is rarely straightforward. Unlike traditional employees, you are classified as an independent contractor, which means you are not automatically covered by your company's workers' compensation insurance. Instead, you must navigate a complex web of app-based injury coverage, the other driver's liability policy, and your own personal auto insurance. Understanding these layers is critical to protecting your rights and securing the compensation you deserve for medical bills, lost income, and vehicle repairs.
The Independent Contractor Classification and Its Impact on Workers' Compensation
When you sign up to drive for a rideshare company like Uber or Lyft, you agree to their terms of service, which typically classify you as an independent contractor. This classification is not just a label; it has profound legal and financial implications. For traditional employees, employers are required to carry workers' compensation insurance, which provides benefits if the employee is injured on the job. These benefits typically cover medical expenses, a portion of lost wages, and disability payments, regardless of who was at fault for the accident. However, because rideshare drivers are independent contractors, they are generally excluded from the company's workers' compensation coverage. This means you cannot file a workers' compensation claim against the rideshare company in the same way an employee would.
This does not mean you are without options. It simply means that the concept of "workers' compensation" for rideshare drivers takes a different form. Instead of a traditional workers' comp claim, you may be able to seek compensation through the rideshare company's commercial liability insurance policy, the at-fault driver's insurance, or your own personal auto policy. However, each of these avenues has specific conditions and limitations. For example, the rideshare company's insurance may only apply during certain periods, such as when you are actively on a trip or waiting for a request. Understanding when and how these policies apply is essential. If you are unsure about your status or the coverage available, consulting with a legal professional can provide clarity. You can also use resources like GoFreeLegal to connect with attorneys who specialize in rideshare accidents.
The independent contractor classification also affects your ability to recover lost wages. Traditional workers' comp provides wage replacement benefits, but as an independent contractor, you must prove your lost income through other means, such as tax returns, bank statements, or app earnings records. This makes documentation even more critical. Without proper evidence, you may struggle to recover the full extent of your financial losses.
App-Based Injury Coverage vs. the Other Driver's Liability Policy
When you are injured in a rideshare accident, there are typically two main sources of compensation: the rideshare company's app-based injury coverage and the at-fault driver's liability insurance. Understanding the difference between these two is crucial for building your claim.
Rideshare companies provide commercial liability insurance coverage that applies during specific periods of your driving session. This coverage is tiered based on your app status. For example, when you are logged into the app but have not yet accepted a ride request (Period 1), coverage is limited, often just matching your personal auto liability limits. Once you accept a request and are en route to pick up a passenger (Period 2), and while you are transporting a passenger (Period 3), the company's coverage is much higher, often up to $1 million for bodily injury and property damage. However, this coverage is primarily liability insurance, meaning it protects you if you are at fault for an accident and someone else is injured. It may also provide uninsured/underinsured motorist coverage and personal injury protection (PIP) in some states, but these benefits vary. Importantly, this is not workers' compensation; it is liability insurance that responds to claims from third parties.
On the other hand, the other driver's liability policy is the insurance of the driver who caused the accident. If the other driver was at fault, you can file a claim directly with their insurance company for your injuries and property damage. This is a third-party claim, and it is not limited by the rideshare company's policy terms. However, you will need to prove that the other driver was negligent and that their negligence caused your injuries. This can be challenging if the other driver disputes fault or if their insurance company denies liability. In some cases, the other driver may be uninsured or underinsured, which means their policy may not be enough to cover your damages. In that scenario, you may need to rely on your own uninsured/underinsured motorist coverage, either from your personal auto policy or the rideshare company's policy, if applicable.
It is important to note that you cannot double-recover for the same damages. If you receive a settlement from the other driver's insurance, you generally cannot also collect the same medical expenses from the rideshare company's policy. However, you may be able to stack coverage in some situations, such as combining PIP benefits from multiple policies. An experienced attorney can help you navigate these complexities and maximize your recovery.
How App Status Affects Coverage: On vs. Off Periods
The level of insurance coverage available to you as a rideshare driver hinges on your app status at the time of the accident. Rideshare companies divide your driving time into three distinct periods, each with different insurance implications. Understanding these periods is essential because they determine which policy responds to your claim.
Period 1: You have the app open and are waiting for a ride request, but you have not accepted a trip. During this time, the rideshare company's liability coverage is typically limited to the state's minimum financial responsibility requirements or your personal auto policy limits, whichever is higher. Some companies also provide contingent comprehensive and collision coverage, but only if you have comprehensive and collision on your personal policy. This period is often the most confusing for drivers because they assume they are fully covered as soon as they log in, but that is not the case.
Period 2: You have accepted a ride request and are en route to pick up the passenger. During this period, the rideshare company's liability coverage jumps to a much higher limit, often $1 million per accident. This coverage applies if you are at fault for an accident that injures someone else. Additionally, some companies provide uninsured/underinsured motorist coverage and PIP during this period, but again, this varies by state and company.
Period 3: You are transporting a passenger. The same high liability limits from Period 2 apply. This is the period with the most comprehensive coverage, as the company assumes greater responsibility while a passenger is in the vehicle.
Off periods: When you are not logged into the app, you are not covered by the rideshare company's insurance at all. During these times, you must rely solely on your personal auto policy. However, many personal auto policies exclude coverage for commercial use, which means if you are driving for rideshare purposes without the app on, you may still be considered to be using your vehicle for business, and your claim could be denied. This is a critical gap that every rideshare driver must address.
To illustrate, imagine you are driving to a friend's house with the app off and you are hit by a negligent driver. Your personal auto policy should respond, but if your insurer discovers you also drive for rideshare, they may investigate whether you were actually off-duty. If you were logged into the app but not on a trip, the rideshare company's limited Period 1 coverage might apply, but it may not be enough. This is why it is vital to have the right personal auto coverage, including rideshare endorsements, to fill the gaps.
Gaps Between Personal Auto Policies and Commercial Coverage
One of the biggest mistakes rideshare drivers make is assuming their personal auto insurance will cover them in all situations. The reality is that most personal auto policies contain exclusions for commercial use, including driving for rideshare companies. If you are involved in an accident while logged into the app, your personal insurer may deny your claim, leaving you without coverage for your injuries or vehicle damage. This gap is precisely why rideshare companies provide their own commercial insurance, but as we have seen, that coverage is not comprehensive and only applies during certain periods.
To bridge this gap, many insurers offer rideshare endorsements or commercial auto policies designed specifically for gig drivers. These policies provide coverage that fills the gaps left by both the rideshare company's insurance and your personal auto policy. For example, a rideshare endorsement might extend your personal policy's coverage to include periods when you are logged into the app but not on a trip, or it might provide uninsured/underinsured motorist coverage that the rideshare company's policy lacks. Without such coverage, you could be left paying out of pocket for medical bills, lost wages, and vehicle repairs.
Another critical gap is uninsured/underinsured motorist (UM/UIM) coverage. Rideshare companies are not required to provide UM/UIM coverage in all states, and even when they do, the limits may be low. If you are hit by a driver with no insurance or insufficient insurance, your own UM/UIM coverage becomes essential. However, many personal auto policies exclude UM/UIM coverage when the vehicle is used for commercial purposes. This means you could be injured by an uninsured driver while driving for rideshare and have no recourse unless you have a specialized policy.
Additionally, medical payments (MedPay) or personal injury protection (PIP) coverage is often excluded on personal policies when the vehicle is used for rideshare. PIP is particularly important in no-fault states, where it pays for medical expenses regardless of fault. If you are injured in a rideshare accident in a no-fault state, you may need to rely on the rideshare company's PIP coverage, if available, or your own PIP if you have a rideshare endorsement. Without it, you could be stuck with significant medical bills.
To protect yourself, review your personal auto policy carefully and consider purchasing a rideshare endorsement or a commercial policy. The extra premium is often worth the peace of mind. If you are already injured and facing coverage disputes, an attorney can help you interpret your policy and fight for the benefits you deserve.
Steps to Preserve Trip Records and App Data as Evidence
In the aftermath of a rideshare accident, evidence is everything. The rideshare company and its insurers will have access to detailed trip data, but you may not. To build a strong claim, you need to preserve as much information as possible about your app status, the trip, and the accident. Here are the critical steps to take immediately after an accident to secure this evidence.
- Take screenshots of the app. Immediately after the accident (if it is safe to do so), take screenshots of your app showing the trip status, the pickup and drop-off locations, the time, and any relevant details. This is crucial because the app may update or the trip may be removed from your history after a certain period. Screenshots provide a timestamped record of your status at the time of the crash.
- Record the accident scene. Use your phone to take photos and videos of the vehicles, the road conditions, traffic signals, and any visible injuries. If there are witnesses, ask for their contact information and record statements if possible. Also, exchange information with the other driver, including their insurance details.
- Report the accident to the rideshare company. Notify the company through the app as soon as possible. They will create a record of the incident and may provide you with a claim number. Be honest and detailed in your report, but do not admit fault or speculate about the cause.
- Request your trip data. You have the right to request your trip data from the rideshare company. This includes GPS logs, timestamps, and fare information. Submit a written request to the company's support or legal department. Keep a copy of your request and any responses.
- Seek medical attention and document everything. Even if you feel fine, see a doctor immediately. Some injuries, like whiplash or concussions, may not show symptoms until hours or days later. Keep all medical records, bills, and receipts. Document your pain levels, missed work, and any other ways the injury has affected your life.
Preserving this evidence is not just about proving what happened; it is also about establishing the extent of your damages. For example, your app data can prove that you were in Period 2 or 3, which triggers the rideshare company's higher liability coverage. Without it, the company might claim you were not on a trip, leaving you with minimal coverage. Similarly, your medical records and lost wage documentation are essential for calculating your claim's value. If you are unsure how to request your data or what to do with it, a lawyer can guide you through the process. For a step-by-step overview of the claims process, see our guide on how to file a car accident compensation claim.
When to Seek Legal Help for Your Rideshare Injury Claim
Rideshare accident claims are inherently complex because they involve multiple insurance policies, disputed liability, and the independent contractor classification. If you are a rideshare driver injured in an accident, you should seriously consider consulting with an attorney, especially if your injuries are significant or if the insurance companies are giving you the runaround. An experienced personal injury lawyer can help you navigate the intricacies of app-based coverage, determine which policies apply, and negotiate with insurers to ensure you receive fair compensation.
Insurance companies, whether the rideshare company's or the other driver's, have teams of adjusters and lawyers working to minimize payouts. They may try to shift blame, deny coverage, or offer a low settlement before you fully understand the extent of your injuries. An attorney can level the playing field, protect your rights, and help you avoid costly mistakes. For example, if you give a recorded statement to an adjuster without legal guidance, you might inadvertently say something that harms your claim. A lawyer can handle all communications and ensure your interests are protected.
Moreover, if your case involves a dispute over your employment status, an attorney can assess whether you have a valid claim for workers' compensation or other benefits. While rare, some states have begun to recognize rideshare drivers as employees for certain purposes, and a lawyer can advise you on the latest legal developments. Even if a traditional workers' comp claim is not available, an attorney can explore alternative theories of liability, such as negligent hiring or inadequate training by the rideshare company.
If you are looking for legal representation, CarInjuryAccident.com can connect you with top-rated attorneys who specialize in rideshare accidents and personal injury. Their patented attorney selection process identifies the top 5% of attorneys each year, ensuring you receive quality representation. You can request a free, no-obligation case evaluation to discuss your options and get personalized advice. The platform is not a law firm and does not provide legal advice, but it serves as a trusted intermediary to help you find the legal help you need.
Being injured as a rideshare driver can feel like a solitary battle against giant corporations and insurance companies. But you are not alone. By understanding the difference between workers' compensation and third-party claims, knowing how your app status affects coverage, and taking immediate steps to preserve evidence, you can strengthen your position and pursue the compensation you deserve. Whether you negotiate with insurers yourself or hire an attorney, acting quickly and documenting everything is key to a successful outcome.