Underinsured Motorist Claim: When At-Fault Policy Is Too Low
Facing a shortfall when the at-fault driver's policy is too low? Learn how to file an underinsured motorist claim. Call (855)-545-2917 for a free case review.
By Calix Rowan
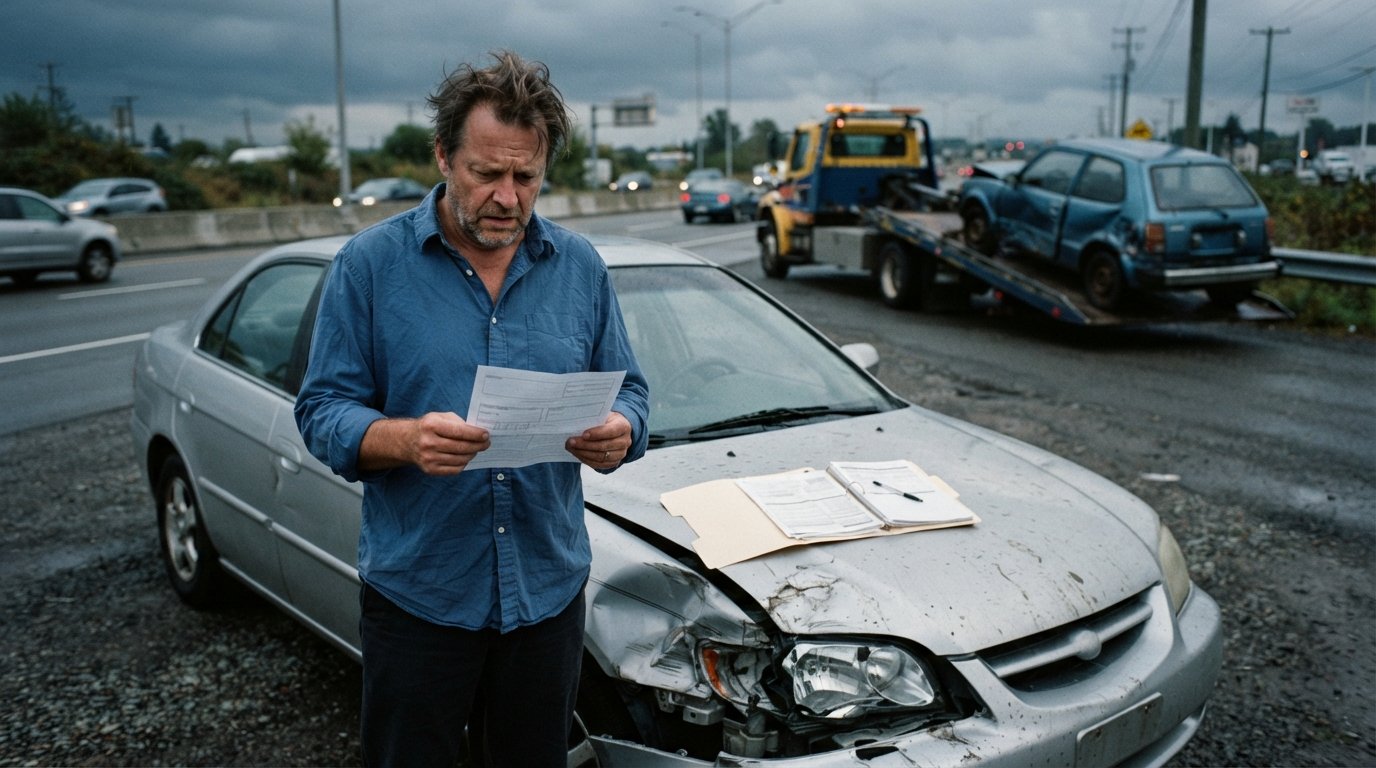
You did everything right after the crash. You exchanged information, called the police, and sought medical care. Then you learned the devastating truth: the at-fault driver's liability policy is far too small to cover your injuries, lost wages, and vehicle damage. The other driver is underinsured, and you are left facing a mountain of bills with a policy that maxes out at $25,000 or $50,000. This scenario is far too common, and it is exactly why underinsured motorist (UIM) coverage exists. But filing an underinsured motorist claim when the at-fault driver's policy is too low is not automatic. Your own insurer will not simply write a check for the difference. You must build a claim, prove the shortfall, and navigate a process designed to minimize what they pay. This guide walks you through the legal mechanics, the practical steps, and the strategic decisions that determine whether you recover the compensation you deserve.
Uninsured vs. Underinsured: Understanding the Critical Difference
Many drivers assume that uninsured and underinsured motorist coverage are the same thing. They are related but distinct. Uninsured motorist (UM) coverage applies when the at-fault driver has no liability insurance at all or when the driver flees the scene in a hit-and-run. Underinsured motorist (UIM) coverage, by contrast, applies when the at-fault driver does have liability insurance, but the policy limits are insufficient to pay for the full extent of your damages. In other words, the other driver is not completely uninsured; they are just not insured enough.
The distinction matters because the claims process and the legal arguments differ. With a UM claim, there is no other policy to collect from, so your insurer steps into the shoes of the at-fault driver. With a UIM claim, there is an existing liability policy, and your UIM coverage sits on top of it. Your insurer will typically want to see that you have exhausted or settled with the at-fault driver's policy before they pay anything. They will also scrutinize whether your damages truly exceed that policy limit, and they will dispute the value of your claim aggressively.
To make matters more confusing, some states treat UIM coverage differently. Some require that you exhaust the at-fault policy by settlement or judgment before UIM kicks in. Others allow you to collect UIM benefits without exhausting the other policy, but they may reduce your UIM recovery by the amount you could have collected. The rules vary significantly by state, which is why understanding your specific policy language and local law is essential. For a step-by-step walkthrough of the claims process when the other driver has no insurance at all, see our guide on uninsured motorist claim steps after a hit by an uninsured driver, which provides a useful comparison for the UIM process.
How UIM Limits Stack on Top of the At-Fault Policy
The core concept of underinsured motorist coverage is that it provides a second layer of protection. Think of the at-fault driver's liability policy as the first layer and your UIM policy as the second. If the at-fault driver has a $25,000 per-person liability limit and your damages are $100,000, the at-fault policy pays its $25,000, and your UIM coverage may pay the remaining $75,000, up to your UIM limit. However, the math is not always that simple, and the way UIM limits are calculated can vary based on state law and your policy wording.
There are two main methods for calculating UIM benefits: the "difference" method and the "stacking" method. Under the difference method, your UIM recovery is the difference between your total damages and the at-fault driver's liability payment, capped at your UIM limit. For example, if your damages are $100,000, the at-fault driver pays $25,000, and you have $50,000 in UIM coverage, you would receive $50,000 from UIM (the difference between $100,000 and $25,000 is $75,000, but your UIM limit caps it at $50,000). Under the stacking method, you can add your UIM limit to the at-fault driver's liability limit, effectively increasing the total available coverage. Some states allow stacking of multiple policies or multiple vehicles, which can significantly increase your recovery.
It is crucial to review your own auto policy to see which method applies. Many policies include language that reduces UIM benefits by any amounts paid by the at-fault driver's liability insurer. This is known as a "setoff" or "reduction" clause. Insurers often interpret these clauses aggressively to minimize payouts. For instance, if you settle with the at-fault driver for $25,000 and your UIM limit is $50,000, the insurer may argue that your UIM recovery is limited to $25,000 (the difference between your UIM limit and the at-fault settlement), even if your damages are much higher. An experienced attorney can challenge overly broad setoff interpretations and ensure you receive the full benefit of your coverage.
Steps to File a UIM Claim with Your Own Insurer
Filing a UIM claim is a multi-step process that requires documentation, patience, and a strategic approach. The following numbered list outlines the key steps, but keep in mind that every case is unique and the order may vary depending on your state's laws and your policy requirements.
- Report the accident and notify your insurer promptly. Most policies require you to notify your insurer of an accident within a reasonable time, and some require immediate notice. Even if you are not at fault, call your insurance company and inform them that you intend to pursue a UIM claim. Provide the at-fault driver's information and the policy limits if you know them. Failing to provide timely notice can give your insurer grounds to deny coverage.
- Document your damages thoroughly. You will need to prove the full extent of your injuries, medical expenses, lost wages, pain and suffering, and property damage. Collect medical records, bills, pay stubs, tax returns, and any other evidence that supports your claim. Keep a detailed journal of your recovery, including how your injuries affect your daily life. This documentation will be the foundation of your UIM claim and will be used to justify a demand that exceeds the at-fault driver's policy limit.
- Determine the at-fault driver's liability limits. You or your attorney can request this information from the at-fault driver's insurer or from your own insurer. In some states, insurers are required to disclose policy limits upon request. Knowing the exact limit is essential because it sets the baseline for your UIM claim. If the at-fault driver's policy is $25,000 and your damages are $100,000, you know there is a $75,000 shortfall to pursue through UIM.
- Exhaust or settle with the at-fault driver's policy. Most UIM policies require that you first exhaust the at-fault driver's liability coverage before your UIM coverage applies. This typically means settling your liability claim against the at-fault driver for the policy limit. Some states require you to obtain a judgment against the at-fault driver, but settlement is more common. Before accepting a settlement, make sure you have a clear understanding of your UIM rights and that the settlement does not inadvertently waive them. Your insurer may need to consent to the settlement, so review your policy and consult an attorney if necessary.
- Submit a UIM claim to your insurer with a demand package. Once you have settled with the at-fault driver, you can present your UIM claim to your own insurer. This typically involves sending a demand letter that outlines the facts of the accident, the at-fault driver's liability, the policy limits, your total damages, and the amount you are seeking from UIM coverage. Include all supporting documentation, such as medical records, bills, and evidence of lost income. Your insurer will then assign an adjuster to evaluate the claim.
After you submit the claim, expect the insurer to investigate, possibly request additional documentation, and eventually make an offer. Do not accept the first offer without scrutinizing it. Insurers often lowball UIM claims, especially when the damages are significant. You have the right to negotiate, and if the insurer acts in bad faith, you may have legal recourse beyond the policy limits.
Why Insurers Dispute UIM Claims and How to Counter
Your own insurer is not on your side when it comes to a UIM claim. Even though you have paid premiums for this coverage, the insurer's goal is to pay as little as possible. There are several common tactics insurers use to dispute or undervalue UIM claims, and understanding them is the first step to countering them.
One common dispute involves the extent of your injuries. The insurer may argue that your medical treatment was excessive, that your injuries pre-existed the accident, or that you failed to mitigate your damages by not following medical advice. To counter this, you need strong medical evidence, including opinions from treating physicians that link your injuries to the accident and justify the treatment you received. An independent medical examination (IME) requested by the insurer can also be challenged, especially if the examiner is known to favor insurers.
Another frequent dispute is the value of your pain and suffering. Insurers often use computer software to generate a low settlement range, ignoring the subjective impact of your injuries. You can counter this by providing detailed personal statements, testimony from family members, and evidence of how your life has changed. Demonstrating that your injuries have affected your ability to work, enjoy hobbies, or perform daily tasks can significantly increase the value of your claim.
Insurers may also dispute liability or comparative fault. Even if the other driver was clearly at fault, the insurer might argue that you contributed to the accident, which in some states reduces your recovery. Or they might argue that a third party was responsible. Thorough accident investigation, witness statements, and police reports can help establish the at-fault driver's full responsibility and rebut comparative fault arguments.
Finally, insurers may dispute the applicability of UIM coverage altogether. They might claim that you did not exhaust the at-fault policy, that you violated a policy condition (such as failing to cooperate), or that a setoff provision reduces your recovery to zero. These are legal arguments that require a careful reading of your policy and state law. An attorney can often resolve these disputes through negotiation or litigation.
If negotiations stall, you may need to demand arbitration or file a lawsuit against your insurer. Most UIM policies include arbitration clauses, which can be faster and less formal than court. However, arbitration has its own risks, and having an attorney represent you is highly advisable. If your insurer's conduct is particularly egregious, you may also have a bad faith claim, which can expose the insurer to damages beyond the policy limit.
Do You Need an Attorney for a UIM Shortfall?
You are not legally required to hire an attorney for a UIM claim, but doing so can make a substantial difference in the outcome. UIM claims are complex, and the stakes are high. Your insurer has teams of adjusters, lawyers, and experts working to minimize your payout. Without legal representation, you are at a significant disadvantage.
An experienced personal injury attorney can handle the entire process, from investigating the accident and documenting your damages to negotiating with the at-fault driver's insurer and pursuing your UIM claim. Attorneys understand the tactics insurers use and can counter them effectively. They can also help you avoid mistakes that could jeopardize your claim, such as giving a recorded statement or signing a release without fully understanding its consequences.
Moreover, attorneys can identify all available sources of recovery. In addition to UIM coverage, there may be umbrella policies, multiple vehicles with stacked coverage, or even commercial policies if the at-fault driver was working at the time of the accident. An attorney can also evaluate whether your insurer has acted in bad faith and pursue additional damages if appropriate.
If you are considering legal representation, CarInjuryAccident.com can connect you with seasoned attorneys who specialize in personal injury and underinsured motorist claims. Their patented attorney selection process identifies top-rated legal professionals, and you can request a free, no-obligation case evaluation. For law firms and attorneys seeking to grow their practice, AttorneyLeads.com provides exclusive, pre-screened legal leads across the United States, connecting motivated consumers with qualified legal professionals. Whether you are a victim seeking help or an attorney looking to serve clients, these resources can streamline the process.
Key Takeaways and Next Steps
An underinsured motorist claim when the at-fault driver's policy is too low is a lifeline, but it is not a guarantee. You must act promptly, document everything, and be prepared to push back against your insurer's tactics. Remember that UIM coverage is a contract between you and your insurer, and you have the right to enforce it. If the insurer delays, denies, or undervalues your claim, do not hesitate to seek legal advice.
Before you accept any settlement or give a statement, review your policy and consult with a professional. The difference between a lowball offer and a fair recovery often comes down to having the right advocate in your corner. With careful preparation and the right support, you can secure the compensation you need to rebuild your life after an accident caused by an underinsured driver.