What to Do If Insurer Records Your Statement After Crash
Already recorded a statement? Learn what to do if insurer records your statement after crash, from declining politely to correcting the record. Call (855)-545-2917 for a free case review.
By Calix Rowan
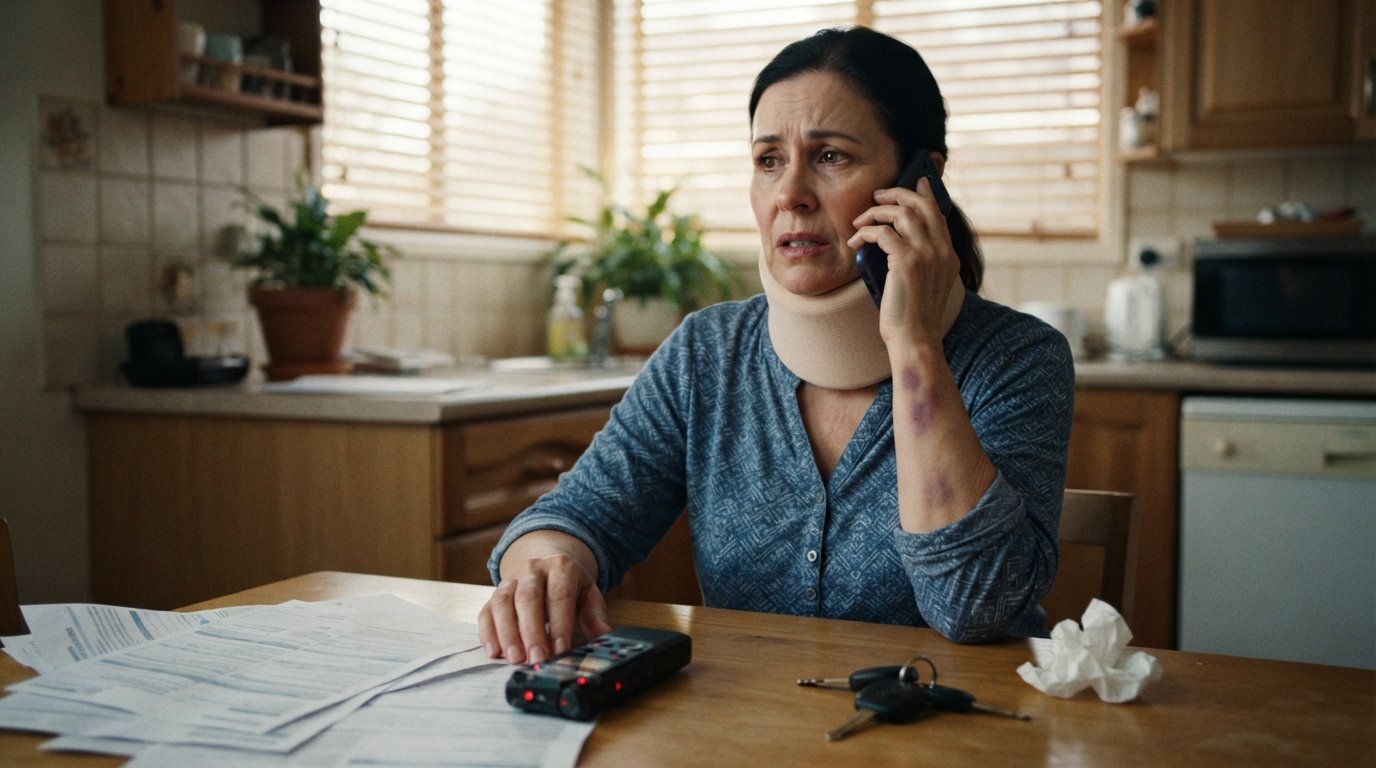
You are still shaking from the crash. Your neck hurts, your car is undrivable, and your phone will not stop ringing. Then the adjuster asks a question that sounds harmless: can we record a quick statement? It feels cooperative to say yes. It feels rude to say no. But that single recorded conversation can quietly reshape your entire injury claim, sometimes before you even know the full extent of your injuries. Knowing what to do if insurer records your statement after crash is not about being difficult. It is about protecting the accuracy of your account while you are still recovering.
Adjusters are trained to sound friendly and helpful. Their job, however, is to protect the insurance company's bottom line. A recorded statement gives them a permanent, quotable version of your words that can be used later to challenge your injuries, your memory, or your credibility. The good news is that you have rights, and you are not required to navigate this alone. A qualified personal injury attorney can step in before the recorder ever turns on.
Why Adjusters Ask for a Recorded Statement So Early
Timing is not an accident. Adjusters usually call within hours or days of a crash, often while you are still in pain, on medication, or trying to line up a rental car. They know that early statements are the easiest to collect and the hardest to walk back. The sooner they lock you into a version of events, the less room you have to account for injuries that take time to surface, like whiplash, herniated discs, or post-concussion symptoms.
There is also a financial incentive behind the call. Insurance companies are businesses. A recorded statement can save them money if it contains anything they can spin as an admission, an inconsistency, or an exaggeration. A single phrase such as "I think I'm fine" or "I didn't see them coming" can later be presented as proof that you were not seriously hurt or that you were partially at fault. Adjusters also compare your statement to police reports, medical records, and witness accounts, hunting for gaps they can exploit during negotiation or litigation.
In some situations, the adjuster is not even working for the other driver's insurer. Your own carrier may ask for a recorded statement as part of a first-party claim, such as uninsured motorist coverage or medical payments coverage. That distinction matters, because your own policy may contain a cooperation clause that technically requires you to assist with the investigation. Even then, you have the right to understand what you are agreeing to and to have counsel present or on the line. For a broader look at how representation changes the dynamics of a serious collision claim, see our guide on why you need a truck accident lawyer after a crash.
The Real Risks of Guessing About Speed, Injuries, or Fault
The biggest danger of an early recorded statement is that you will be asked to answer questions you simply cannot answer accurately yet. You may not know how fast the other car was going. You may not know whether your back pain is a strain or a disc injury. You may not know whether the other driver ran the light or whether you both had a green. Guessing feels harmless in the moment, but every guess becomes a permanent record.
Consider how a few common answers can backfire:
- "I'm not really hurt, just sore." Later medical imaging shows a herniated disc, and the adjuster argues you admitted there was no real injury.
- "I think I was going about 10 over the limit." That estimate can be used to assign you partial fault, reducing your recovery even if the other driver caused the crash.
- "I didn't see the other car." The adjuster may twist this into a failure to keep a proper lookout, shifting blame onto you.
- "I've had back pain before." A pre-existing condition becomes the excuse to deny or minimize your current injury claim.
Once those words are recorded, you cannot unring the bell. You can clarify later, but clarification often sounds like backpedaling to a jury or an arbitrator. The safer approach is to avoid giving definitive answers about speed, fault, or injury severity until you have spoken with a doctor and a lawyer. Your memory of the crash is also freshest in the first few days, but your understanding of your injuries is often clearest weeks later. A recorded statement forces you to freeze one part of the story while the other part is still unfolding.
Your Insurer vs. the Other Driver's Insurer
Not all recorded statement requests carry the same weight. The other driver's insurance company has no contractual right to demand a recorded statement from you. You are a third party to their policy. They can ask, and you can politely decline or defer until you have legal representation. In practice, many injury attorneys advise clients not to give a recorded statement to the at-fault driver's insurer at all, at least not without counsel guiding the conversation.
Your own insurance company is a different story. If you are filing a claim under your own policy, such as uninsured motorist coverage, medical payments, or collision coverage, your policy likely includes a duty to cooperate with the investigation. That does not mean you must submit to an immediate, unrecorded, wide-ranging interrogation. It means you should review your policy language, understand your obligations, and consider having an attorney communicate with your insurer on your behalf. Many carriers will accept a written statement, a sworn affidavit, or a guided interview with counsel present.
There is also the issue of bad faith. If your own insurer mishandles your claim, delays payment without reason, or misrepresents your policy, you may have a bad faith claim. Recorded statements can become evidence in that dispute. A lawyer can help you document what was asked, what was said, and whether the insurer acted unfairly. If you are dealing with a carrier that seems more interested in trapping you than paying you, it may be time to bring in professional help. Platforms like AttorneyLeads connect law firms with pre-screened legal prospects, but for consumers, the faster path is often a direct consultation with a personal injury attorney who handles bad faith issues.
How to Request the Statement in Writing or Decline
You do not have to say yes on the spot. Adjusters often pressure crash victims by implying that a delay will hurt the claim. In reality, a short, polite pause while you get legal advice rarely damages a legitimate claim. What you say matters more than when you say it. If you are not ready, or you do not have counsel yet, you can decline the recorded format and offer alternatives.
Here is a practical sequence you can follow when an adjuster calls:
- Do not give a recorded statement on the first call. Thank the adjuster, confirm your name and contact information, and say you will follow up in writing.
- Ask for the request in writing. Request an email or letter that states exactly what information the insurer wants and under which policy provision.
- Review your policy. Check whether your own policy requires cooperation and whether it specifies the form of the statement.
- Consult an attorney before agreeing to anything recorded. A lawyer can attend the statement, prepare you for likely questions, and object to improper inquiries.
- Offer a written statement or guided interview instead. Many insurers will accept a signed narrative or a question-and-answer session with counsel present.
If the adjuster insists on recording, you can say something like: "I am willing to cooperate, but I would like my attorney present for any recorded statement. Please send the request in writing and I will have my lawyer contact you." That response is professional, preserves your cooperation obligations, and puts the insurer on notice that you are represented. If you do not yet have a lawyer, CarInjuryAccident.com can help you connect with participating attorneys who handle car accident and personal injury claims. The platform offers a free, confidential case evaluation with no obligation to hire.
It also helps to keep a log of every call. Write down the date, time, adjuster name, and what was discussed. If the adjuster becomes pushy or misstates your policy, that log becomes valuable evidence. Do not rely on memory alone when an insurer is building a file against you.
Correcting or Clarifying a Statement You Already Gave
Maybe you already gave a recorded statement before you knew better. It happens to thousands of crash victims every year. The important question is what you can do now. You cannot erase the recording, but you can clarify, supplement, or correct it. The key is to act quickly, in writing, and with documentation that explains why your earlier answers were incomplete or mistaken.
Start by requesting a copy of the recorded statement or a transcript. Insurers sometimes resist, but many will provide it, especially once you are represented. Review it carefully. Note every answer that is inaccurate, incomplete, or based on a guess. Then prepare a written correction that explains, in plain language, what you meant and why the earlier answer was wrong. For example, if you said you were not injured but later sought treatment, explain that you initially thought you were sore but symptoms worsened and you were diagnosed with a specific condition on a specific date.
Do not simply send a letter saying "I take it all back." That rarely helps. Instead, provide context and evidence. Attach medical records, repair estimates, or witness information that supports the corrected version. If you were on pain medication during the original statement, say so. If you were rushed, confused, or pressured, document that as well. A lawyer can help you draft a correction that is persuasive rather than defensive.
In some cases, the insurer will argue that your later correction is self-serving. That is why timing and documentation matter. The sooner you correct the record, the more credible the correction appears. If you wait until litigation, the insurer will argue you changed your story only after seeing the medical bills. An attorney can also use the correction process to highlight inconsistencies in the insurer's own handling of the claim, which may support a bad faith argument down the road.
Protecting Your Claim Moving Forward
After a crash, the adjuster's early call is often the first of many attempts to shape the narrative. You can expect follow-up calls, requests for medical authorizations, and pressure to settle quickly. Each of these steps carries risk. A recorded statement is just one piece of a larger claims process that rewards preparation and punishes improvisation.
Here are a few habits that protect your claim:
- Do not sign medical authorizations that let the insurer access your entire medical history. Limit releases to the treatment related to the crash.
- Do not accept a quick settlement before you know the full extent of your injuries. Once you sign a release, you cannot reopen the claim.
- Document everything: photos, witness names, medical visits, missed work, and out-of-pocket expenses.
- Tell your doctors about every symptom, even ones that seem minor. The medical record is the backbone of your injury claim.
- Keep a written log of every conversation with any insurer, including the date, time, and substance of the call.
If the insurer has already recorded your statement, do not panic. You still have options. An experienced personal injury attorney can review the transcript, identify the damage, and build a strategy to correct or contextualize your words. In many cases, the rest of the evidence (police report, medical records, vehicle damage, witness statements) carries more weight than a single early statement. The adjuster knows that. That is why they push so hard to get it on tape.
Finally, remember that you are not required to face this process alone. CarInjuryAccident.com connects crash victims with a network of seasoned attorneys across personal injury, car accidents, and related practice areas. The platform uses a patented attorney selection process to identify top-rated legal professionals, and it offers free, confidential case evaluations with no obligation to hire. If you are unsure whether to give a recorded statement, or you have already given one and want to know how to fix it, a consultation with a participating attorney is a low-risk, high-value next step. You can also reach the team directly at (855)-545-2917 to discuss your situation and get connected with the right legal help.